
It’s normal for businesses to run into cash flow gaps, and this is especially common in Houston’s surging economy, where opportunities move quickly. Whether you’re starting a business or already established, most companies eventually need financing options beyond what’s sitting in the bank.
A line of credit solves this by giving you a credit limit you can draw from all year round whenever you need cash. You draw what a situation calls for, pay interest on just that amount, and once it’s repaid, you can use the same credit again.
That said, the lender you choose plays a major role, influencing your APR, funding time, and overall ease of qualification. Here’s what we recommend looking for in a line of credit lender:
- Check what it takes to get approved. Plenty of lenders set a bar most Houston businesses can’t clear, asking for years of profitability, a spotless credit history, and personal guarantees. Most businesses find themselves months into the application process only to get rejected. Choose a lender with more realistic credit approval standards.
- Look beyond a lender’s promised turnaround time. Most lenders’ websites claim fast approval, but it’s very rare for them to actually live up to their promises because of all the paperwork they must evaluate during underwriting. To gauge a lender’s real closing speed, check their paperwork requirements. Go with one that asks for minimal paperwork because they typically close quicker.
- Don’t partner with lenders who pressure you to accept. Lenders with expensive offers will rush you to sign and close the deal because they don’t want you to find more competitive offers. Lenders with the best offers won’t mind you taking your time or comparing elsewhere.
- Find out what credit limit you’d actually receive. A lot of lenders are risk-averse and keep limits thin relative to your revenue, which can mean qualifying for a working capital line of credit that still isn’t enough to cover payroll or a real expense. We recommend partnering with lenders who are less risk-averse.
This guide compares Houston’s top line of credit lenders against the four criteria above. We’ll start with ourselves at Redline Capital and how we designed our process to be easy to qualify for, fast to close, competitively priced, and generous with credit limits.
Enter your numbers into our loan calculator for an instant look at the rates, terms, and credit limits your business qualifies for.
1. Redline Capital: Fast Funding for Houston Businesses
We started Redline Capital because we saw that traditional business financing was too slow and bureaucratic for how businesses operate. When a cash flow gap needs bridging in days, not months, a bank that takes 60 to 90 days to fund a line of credit isn’t an option.
Since founding Redline Capital, we’ve closed over $100 million in lines of credit, most of it funded the same day the business applied. That speed has helped businesses across Houston cover payroll, take on new opportunities, and handle whatever came up, without waiting weeks to find out if they’d get approved.


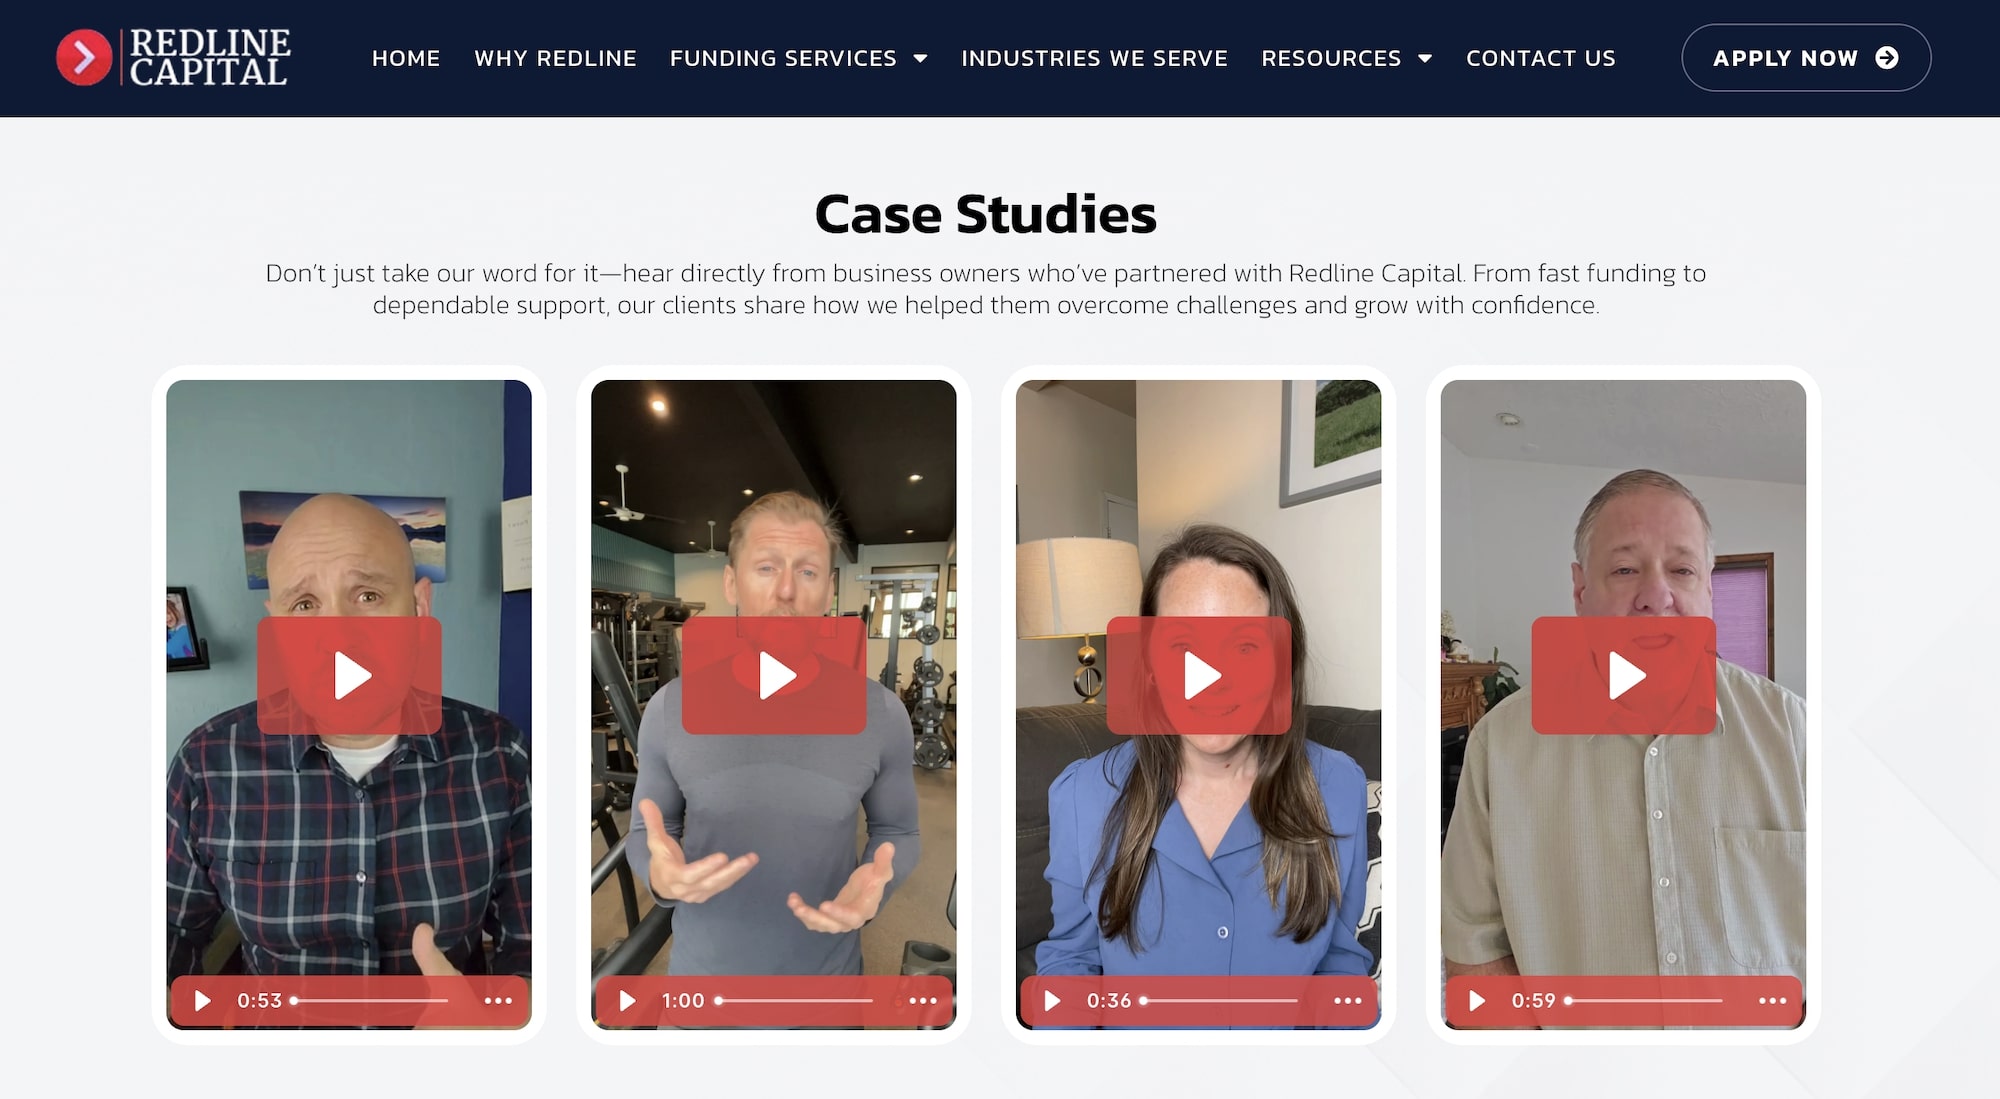
You can also head over to our case studies page to hear from our customers firsthand:
Our Requirements Are Realistic, and We Approve Over 80% of Businesses
Getting approved for a bank line of credit is extremely difficult because most banks want a near-flawless financial history before they’ll even consider an application. As a result, fewer than 1 in 8 businesses get approved for a line of credit at a large bank.
Qualification criteria are worth checking before you commit, so you don’t spend weeks on an application only to get rejected. That wastes time you could have spent applying somewhere realistic from the start.
We built Redline to help businesses that couldn’t qualify with a bank still secure the small business loans and lines of credit they need. Qualifying comes down to three things:
- $30,000 or more in monthly revenue
- At least 12 months in operation
- Being based in the U.S.
That bar is considerably easier to clear than a bank’s, and it shows in our approval rate. We approve more than 80% of the businesses that apply with us for a line of credit.
Read more: Business Loan Denied? Here’s How to Get Funded Same-Day
We Only Need 4 Months of Bank Statements and Can Close the Same Day You Apply
We don’t recommend taking a lender’s advertised closing speed at face value. We know from talking with borrowers that most lenders don’t live up to it, and you usually only find that out once you’re already in the middle of an application.
Instead, check how much paperwork they ask for because it is the most accurate predictor of closing speed. The more documents a lender asks for, the longer it takes to evaluate and underwrite your application, and the longer you’ll wait for a decision.
At Redline Capital, because we only review your revenue, we only need four months of bank statements. That’s it; no tax returns, collateral appraisals, or years of financials to dig up. This lets us close most loans the same day you apply.
Read more: How to Use a Business Line of Credit: Smart Uses & Mistakes
We Never Pressure You Into Accepting an Offer
If a lender pressures you to accept an offer quickly, that’s usually a sign it’s expensive. They don’t want you comparing it elsewhere and finding something better.
With us, you’ll never feel that pressure. We’re confident in our offers and encourage businesses who apply with us to shop around. We know that in most cases, when businesses shop around, they end up coming back to us because of the quality of our offers.
We’re able to secure you better offers because we’re a broker with over 10 years of experience working with the most established business lenders such as OnDeck, Headway Capital, Rapid Finance, and more.
We’ve sent them hundreds of millions of dollars in applications, which grows their business, and in return, they give our applicants better pricing and terms.
We Can Extend Larger Credit Limits Than Most Lenders
Most banks and lenders offer extremely small credit limits, often just 10% to 30% of your monthly revenue. That can leave you approved for a line of credit that still isn’t enough to cover payroll, restock inventory, or repair a broken piece of equipment.
We take a different approach. Because we’re not weighing your credit score, collateral, or profit margins, we can extend credit lines up to $750,000, or as much as 200% of your monthly revenue.
Secure a Same-day Line of Credit at Competitive Rates
Use our automated line of credit pricer to see what rates, amounts, and limits your business qualifies for. From there, submit four months of bank statements, and we’ll email you line of credit offers that can fund as quickly as the same day.
Alternatives to Consider in Houston
2. PrimeWay Federal Credit Union
PrimeWay Federal Credit Union has served Houston, TX, since 1937, when it started as Houston Telephone Federal Credit Union. Today it operates six branches across the city, offering business banking services alongside personal accounts, including checking, credit cards, and overdraft protection for members who want it linked to their line of credit.
To open a business line of credit, you first need to qualify for membership, which generally means living, working, worshipping, or attending school in the Houston area, or belonging to an affiliated group.
That membership requirement is worth knowing upfront, since it means a business outside PrimeWay’s service area can’t access the product no matter how strong its financials are. As a smaller credit union, its lines of credit also tend to top out at more modest amounts than what a larger bank or online lender would extend.
3. Texas Bay Credit Union
Texas Bay Credit Union is a Houston-based, not-for-profit financial cooperative that offers business checking accounts, business credit cards, and a business line of credit designed to help members manage day-to-day cash flow.
Qualifying works the same way it does at most credit unions: you become a member first, typically by living or working in the greater Houston area, then apply for the line of credit itself.
Because Texas Bay is member-owned rather than built for scale, its business line of credit tends to carry a lower ceiling than what a bank or a direct online lender offers. A fast-growing business that quickly outpaces a modest limit may find itself needing to look elsewhere sooner than expected.
4. PeopleFund
PeopleFund is a non-profit lender built to expand access to capital for underserved communities across Texas, including Houston. Alongside term loans and equipment financing, PeopleFund offers revolving lines of credit with flexible underwriting, no prepayment penalties, and one-on-one support from a lending team that also provides business coaching.
Because PeopleFund is mission-driven rather than profit-driven, it tends to work with businesses that a conventional bank might turn away, including newer companies with limited credit history.
That flexibility comes with trade-offs. Approval can take longer than what an online lender offers, since PeopleFund emphasizes relationship-based underwriting and business coaching over instant decisions. Other Houston nonprofits, like LiftFund, offer similar mission-driven support, though LiftFund’s own lineup leans toward term loans rather than a revolving line of credit.
5. Plains State Bank
Plains State Bank is a community bank serving the Houston metropolitan area, offering working capital lines of credit products alongside term loans, commercial real estate loans, construction loans, and equipment financing, with amounts ranging from $75,000 to $15,000,000 depending on the product.
The bank also works with entrepreneurs looking to start a business, pairing SBA-guaranteed programs with more flexible terms and lower down payments for newer companies without an extensive track record.
As a relationship-driven community bank, Plains State pairs each business with a local lender rather than routing applications through an automated system. That personal approach can mean a slower, more document-heavy process than what a business would experience applying with a revenue-based lender online.