
Florida businesses often turn to lines of credit to cover working capital needs, purchase inventory, or manage accounts payable while waiting for clients to pay or savings to build up.
A line of credit’s biggest advantage over other financing products is that it’s revolving. Unlike a traditional loan, you only pay interest on the amount you use, not the full amount you’re approved for. Once you repay it, your credit line replenishes, so you can use it again without reapplying.
Those benefits aside, most Florida line of credit lenders have key limitations worth considering:
- Strict qualification criteria: Florida banks and credit unions typically require near-perfect credit scores, large profit margins, and years of operating history, plus membership requirements for credit unions. Most businesses fail to qualify, and those that do typically don’t qualify for the amount they need.
- Long funding times: Most banks and credit unions ask for extensive paperwork, such as tax returns, financial statements, and personal guarantees, to determine creditworthiness before extending credit. This takes time for you to gather and for them to evaluate. As a result, funding can take upwards of 60 to 90 days, making it impractical if you need quick access to capital for unexpected expenses.
To help Florida businesses navigate these problems and close quickly and with certainty, we break down the factors worth considering before choosing a line of credit, then compare how Florida lenders measure up.
Who are we? Redline Capital has helped Florida businesses secure hundreds of millions of dollars in lines of credit. If you’d like to see the interest rates, terms, and credit amounts you qualify for, use our automated pricer to generate instant quotes.
What to Evaluate Before Choosing a Business Line of Credit
How Easy Is It to Qualify?
As we mentioned above, most lines of credit products have qualification requirements that price out newer or smaller businesses.
Banks and credit unions typically want perfect credit, long operating histories, large profit margins, business or personal assets as collateral, and more. That’s why only 13% of businesses qualify for bank loans.
So before applying, it’s worth checking what a lender actually requires and how smooth their credit approval process is. Partner with a lender that qualifies you based on real, current performance, as it gives you a realistic shot at approval.
What Are Their Paperwork Requirements?
It’s also worth checking how much paperwork a lender needs, since it’s the most reliable indicator of how quickly you can get funded.
Lenders that ask for piles of paperwork, such as tax returns, balance sheets, accounts receivable documentation, and personal guarantees, rarely fund quickly, since underwriting all of it takes time. That’s why most banks and credit unions need around 60 to 90 days to close.
Look for lenders with fewer paperwork requirements, since that typically means a faster path to funding.
Are They an Established Broker or a Direct Lender?
It’s normal to think that skipping middlemen and going straight to a lender will get you a better deal because there are fewer parties and fees involved. That’s the case with newer, lower-quality brokers, but established ones can help you secure lower rates than going directly to a lender.
That’s because lenders extend better terms to sources that deliver large volumes of business. A broker who has built that kind of track record over time carries weight that no individual applicant can bring on their own, and lenders compensate for it accordingly with lower rates, larger credit limits, and better loan products.
The result is that applying through the right broker lets you benefit from all the business they’ve sent their lenders, leading to better offers.
Do They Pressure You to Accept Their Offers?
How a lender follows up after sending an offer tells you almost as much as the offer itself.
When a lender pressures you to sign quickly, it’s usually because they know their offer won’t hold up if you have time to compare it elsewhere. So they resort to repeated calls, invented deadlines, or claims that another business is waiting on the same funds — tactics meant to lock in your signature before you look elsewhere.
Lenders with genuinely competitive rates give you room to compare offers, ask questions, and make your decision without pressure. They can afford that patience because they know their terms will hold up.
5 Business Line of Credit Lenders in Florida Compared
1. Redline Capital: Same-day Business Lines of Credit at Low Rates
Redline Capital is a revenue-based financing company, built as an alternative to community banks and online lenders that ask for far more than most growing businesses can offer upfront.
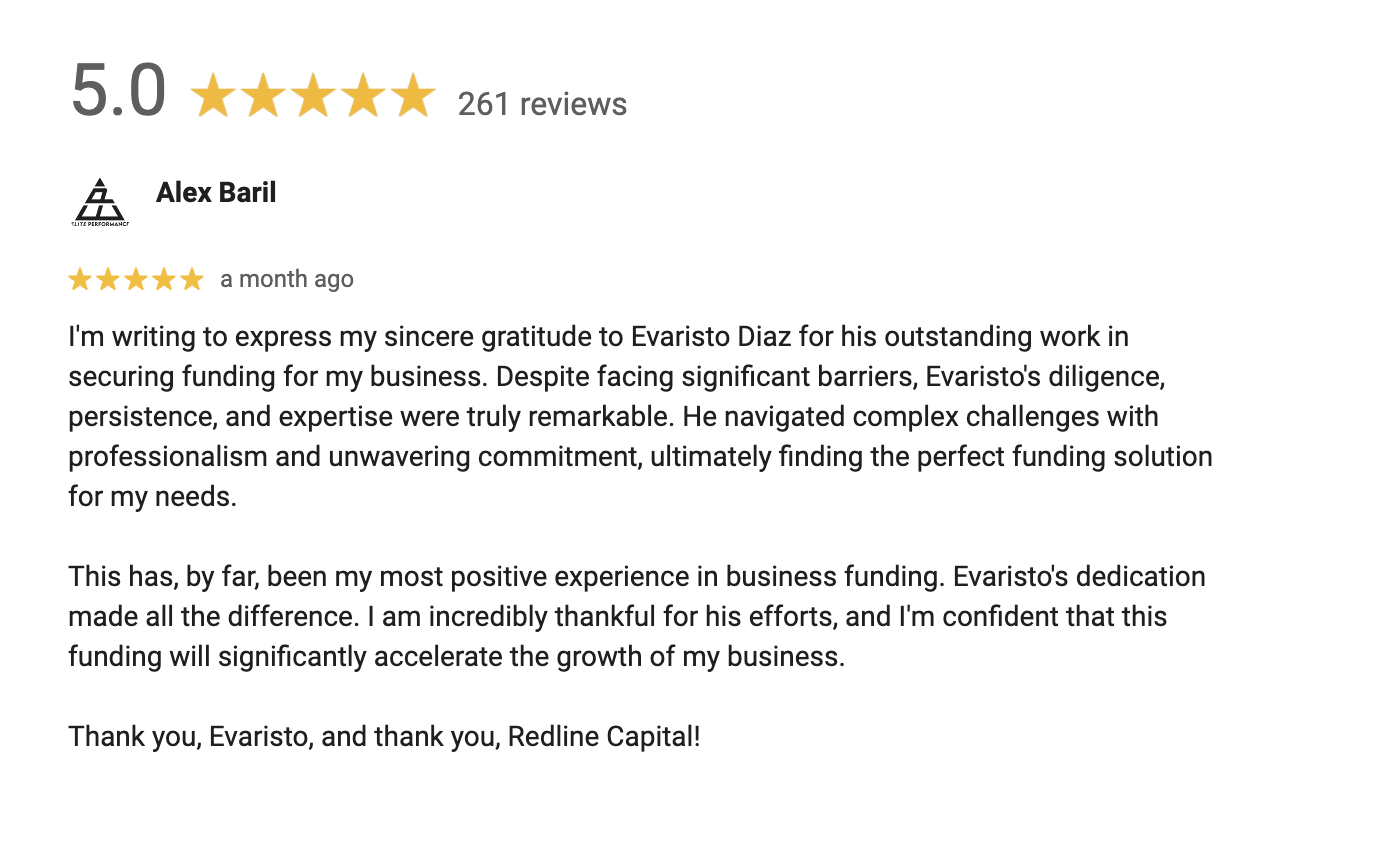
Here’s how borrowers describe their experience with Redline Capital:


Our Qualification Is Extremely Accessible; 80%+ of Businesses That Apply With Us Get Approved
We designed our qualification criteria to help businesses that were turned down by banks and credit unions still secure the financing they need.
To be eligible, all you need is $30,000 or more in monthly revenue, at least 12 months in operation, and be based in the U.S. Your credit score, profit margins, tax returns, and collateral don’t factor into the decision.
As a result, we approve more than 80% of the businesses that apply, well above the 13% that banks and credit unions approve.
Read more: How Does Revenue-Based Financing Work?
We Only Ask for 4 Months of Bank Statements and Can Close the Same Day You Apply
We keep paperwork to a minimum because our qualification is based on revenue, not credit history, collateral, or profit margins. All we ask for is four months of bank statements to verify your revenue, nothing more.
That’s also why we’re able to send offers immediately after you apply, and fund on the same day you accept. Less paperwork isn’t just easier on you; it’s what makes fast funding possible in the first place.
We Can Help You Secure Lower Rates and Larger Credit Limits
Redline Capital has spent years sending a steady volume of qualified business to top lenders, including Headway Capital, Rapid Finance, and OnDeck. In return, they offer our applicants stronger pricing and higher credit limits than businesses typically secure applying on their own.
When you apply through Redline, you draw on relationships with lenders that you didn’t have to spend years building, resulting in better rates than a standard term loan or line of credit product from a single lender.
Read more: Why Use Revenue-Based Financing Instead of Debt Financing?
We Are Confident in Our Offers and Never Pressure Businesses Into Accepting Them
We don’t rely on repeated calls or invented deadlines to get you to accept our offer. Once we send it, we give you the space to review it, compare it, and decide on your own timeline.
We can afford this approach because our offers are strong enough to hold up against anyone else’s. We know that once you shop the market, you’re likely to come back to us, so there’s no need for us to pressure you or rely on tactics that other lenders use to rush your decision.
Get a Fast, Low-Cost Business Line of Credit with Redline Capital
Drop a few details about your business into our loan calculator and find out what rates, credit limits, and terms you qualify for.
2. Florida Credit Union

Florida Credit Union structures its secured and unsecured business line of credit as a committed facility you can draw, repay, and borrow against again.
They transfer funds into your checking account in $50 increments, and linking the line to your checking account gives you overdraft protection against costly fees.
As part of its broader suite of business services, they also offer equipment loans, a business credit card with no annual fee, and are approved to offer SBA loans through the SBA Express Program.
Qualifying starts with membership. You need to live, work, or operate your business in one of the 48 Florida counties Florida Credit Union serves, plus meet its underwriting criteria for creditworthiness, income, and operating history.
Because membership comes first, a business outside those 48 counties cannot access this line of credit regardless of how strong its financials are. Joining also requires opening a share account with an initial deposit before you can even apply, adding a step that an online lender wouldn’t require.
3. Seacoast Bank

Seacoast Bank pairs its business line of credit with a commercial lending team of experienced bankers and local decision-making, positioning the product for short-term expenses like payroll, inventory purchases, and unexpected costs.
Businesses can link the line to a Seacoast Business Checking account for automatic payments, and interest is charged only on the amount drawn rather than the full credit limit.
To apply, a business generally needs to be Florida-based and in operation for at least three years, and applicants are asked to provide three years of tax returns, personal financial statements, and ownership information.
That three-year minimum rules out newer businesses and startups outright, regardless of current revenue or performance. The volume of documentation required, three years of tax returns and full financial statements, also means a longer runway before a decision.
4. Hancock Whitney Bank (formerly One Florida Bank)

One Florida Bank, which merged into Hancock Whitney Bank on August 1, 2026, frames its business line of credit as part of a broader working capital and asset lending relationship, letting a business borrow, repay, and reborrow funds to match its collection cycle.
Lines can be structured with a longer maturity date, and businesses have the option to convert all or part of an outstanding balance into a term loan. The bank also offers U.S. Small Business Administration loans through the 7(a) and 504 programs for businesses that need longer-term financing.
Every line of credit is subject to credit approval, and One Florida Bank doesn’t publish a fixed set of qualification thresholds, instead evaluating each business individually through its lending team.
Because eligibility isn’t laid out upfront, a business has to start a conversation with a local banker just to find out whether it qualifies, let alone what terms it might receive. That relationship-first approach can work well for an established business, but it adds a step that a business comparing several options quickly may not have time for.
5. Cogent Bank

Cogent Bank rounds out its commercial line of credit with purchase order financing, letting a business direct funds straight to a supplier to fulfill a large order without straining its cash flow. The bank is Florida-chartered, with local decision-making handled by bankers based in the communities it serves. It also offers commercial real estate loans and equipment financing for businesses that need to fund property or asset purchases alongside working capital.
Applicants are generally asked to provide business financial statements, tax returns, ownership information, and details on how the funds will be used.
As with other relationship-driven banks, Cogent doesn’t list specific credit score or revenue thresholds for its business line of credit, so a business won’t know exactly where it stands until it applies and works through underwriting with a banker. That process, plus the standard documentation request, generally takes longer than what a business would experience applying with a revenue-based lender online.