
Retail is one of the most seasonal sectors. Sales spike around Christmas, back-to-school, and Easter, then drop off once those seasons pass. Yet businesses must buy inventory ahead of demand and pay bills during slow months, regardless of whether they have the cash.
As a result, retail businesses commonly turn to lines of credit to bridge cash flow gaps. A revolving line of credit gives you access to a balance you can draw from year-round, pay interest only on what you use, and reuse once you repay it. No reapplying required.
Despite the benefits of a line of credit, who you get one from matters just as much. It determines how easy it is to qualify, how fast you get funded, and how much you end up paying in interest rates. Here’s what we suggest checking when choosing a lender:
- Look at what it actually takes to qualify, so you don’t spend weeks on an application only to get rejected. Many lenders set the bar extremely high (e.g., near-perfect personal credit, a lengthy time in business, personal guarantees), shutting out most retailers. Go with a lender that has a more realistic bar, as it gives you a fair shot.
- Don’t take a lender’s advertised speed at face value. Almost all lenders promise fast funding, but most don’t deliver. Paperwork volume is a much better predictor of funding speed. The more a lender asks for, the longer underwriting drags on, and the longer you’ll wait.
- Pay attention to how a lender behaves after sending an offer. One that’s confident in its pricing has no reason to rush you; they’ll let you compare it elsewhere and take your time. A lender pushing for a fast signature is usually compensating for an expensive offer by trying to prevent you from shopping around.
- Check the credit limit you qualify for. Many lenders are overly risk-averse and only extend a small slice of your monthly revenue. So you might qualify, but still not have enough to cover an inventory order or expense. Choose a lender that is willing to lend the amount you actually need.
We put this guide together to help retail businesses qualify faster, avoid unnecessary back-and-forth, and land the most competitive rate they can.
Run your numbers through our loan calculator for an instant look at the rates, terms, and credit limits your business qualifies for.
1. Redline Capital: Lines of Credit Designed Around Retail’s Busiest Seasons
We founded Redline Capital to solve the speed problem we kept seeing in business loan financing. Retailers facing a sudden inventory need or an unexpected sales swing couldn’t get funded fast enough to respond.
To date, we’ve closed over $100 million in lines of credit, most of it funded the same day or the next, allowing hundreds of retail businesses across the U.S. to buy inventory, make payroll, and cover whatever came up, right when they needed to.


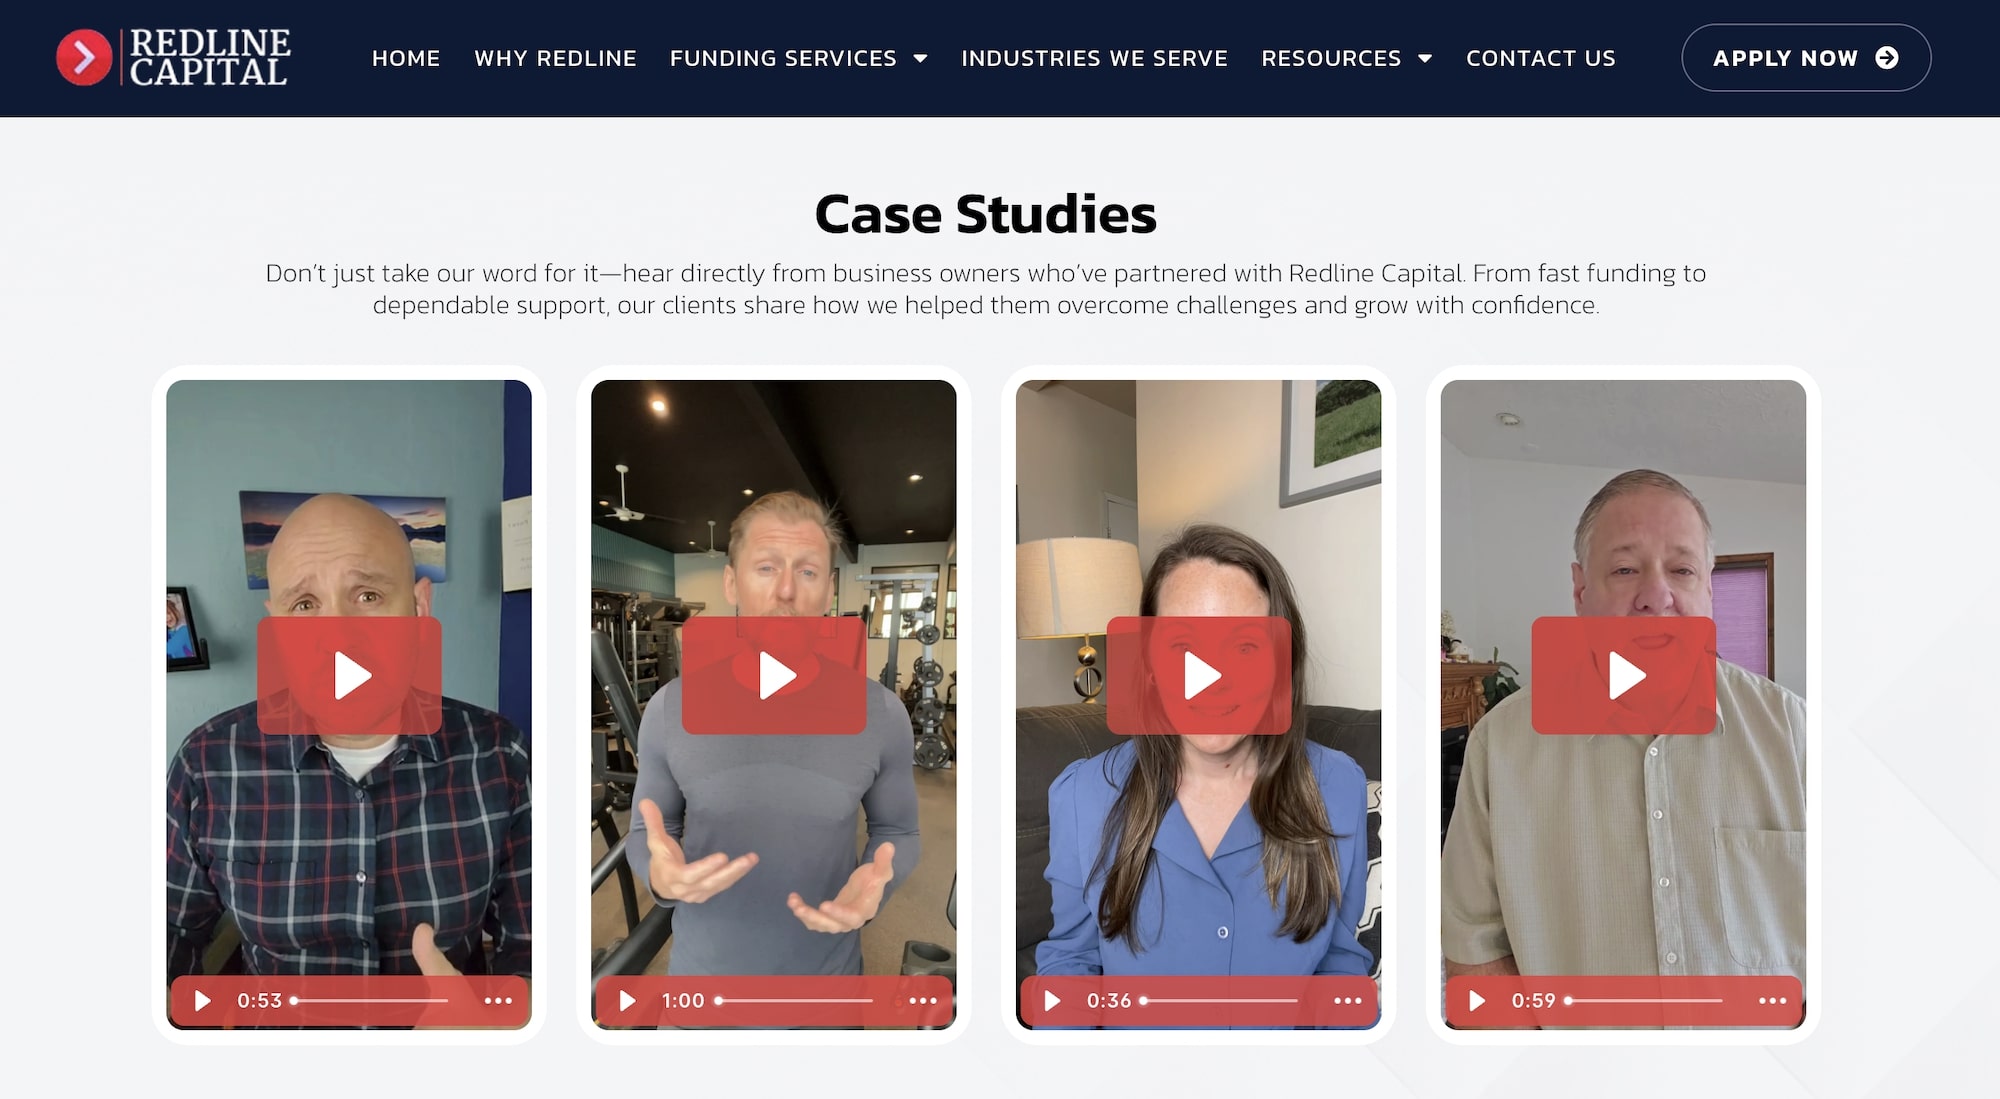
You can also hear directly from our borrowers on our case studies page:
Here’s how Redline Capital checks the four boxes above:
Our Requirements are Accessible, and We Approve Over 80% of Businesses
A small business line of credit is one of the hardest financing products to qualify for, as most lenders want your business to be in near-perfect financial condition, with strong annual revenue and a clean credit history to match.
So, we recommend checking a lender’s requirements before committing because you don’t want to spend weeks or months on a credit application only to get turned down. That wastes time you could have spent applying somewhere realistic from the start.
With Redline, qualifying is much easier because it boils down to three things: $30,000 or more in monthly revenue, at least 12 months in operation, and being based in the U.S. No credit score, no profit margin requirement, and no years of financial history to prove.
That makes us considerably easier to qualify with than a bank or credit union. We approve more than 80% of the retail businesses that apply.
We Only Need 4 Months of Bank Statements and Can Close the Same Day You Apply
You’ll notice that most lenders promise fast funding on their website. But from what we hear from borrowers, most don’t deliver, and you often don’t find out until you’re already in the middle of an application.
Instead of taking them at their word, paperwork requirements are a better indicator of a lender’s funding speed. Most banks want years of tax returns and full financial statements, sometimes even a balance sheet breaking down your business assets, before they’ll give you a decision. The more a lender asks for, the longer underwriting takes, and the longer you’ll actually wait.
At Redline, we only ask for four months of statements from your business bank account that confirm you meet the $30,000 per month revenue minimum, nothing more. This lets us close most loans the same day the business applies.
We Believe in The Quality of Our Offers and Never Pressure You Into Signing
If a lender pressures you to accept an offer quickly, that’s usually a sign the APR is expensive. They don’t want you shopping around and finding something more affordable.
Lenders with genuinely competitive offers don’t need to do this. They’re happy to let you compare and take your time.
At Redline, we actually want you to shop around. We know that once businesses compare their options, they usually come back to us.
That’s because we’re an established broker. Over the years, we’ve sent millions of dollars of qualified business to lenders like OnDeck, Headway Capital, and Rapid Finance, and in return, they extend our applicants better rates and repayment terms than a business would get walking in on its own.
Read more: How to Use a Business Line of Credit: Smart Uses & Mistakes
Check the Credit Limit You’d Actually Qualify For
Most banks, credit unions, and lenders only extend 10% to 30% of your monthly revenue as a credit line. Getting anywhere close to 50% usually requires near-perfect financials, strong credit, healthy margins, and collateral to back it up.
That leaves a gap for businesses that do qualify. You can clear a lender’s bar and still walk away with a credit limit too small to cover payroll, restock inventory, or handle an outstanding balance on a supplier order.
With Redline Capital, businesses regularly get up to 200% of their monthly revenue in credit. We can offer that because we don’t limit you based on credit score, profit margins, or collateral the way a bank would.
Secure a Fast Retail Line of Credit at Competitive Rates with Redline Capital
Generate instant quotes and see what you qualify for by entering some details about your business into our automated loan calculator.
2. Wells Fargo
Wells Fargo is one of the largest banks in the United States, and it segments its business lines of credit by company size and operating time rather than offering a single credit product.
The unsecured lines of credit option, BusinessLine, goes up to $100,000 and suits day-to-day operating expenses, while the secured line of credit option, Prime Line of Credit, extends to higher limits for established businesses willing to pledge collateral. Both are revolving, so you draw, repay, and draw again throughout the term.
As a full-service bank, Wells Fargo can also pair a line with overdraft protection on a linked business checking account.
Eligibility for BusinessLine starts at six months in business, and rates run on a variable rate basis, between prime rate plus 1.75% and prime plus 9.75% depending on your personal and business credit. Wells Fargo also requires a personal guarantee from any owner holding 25% or more of the business.
The interest rate you get depends on your business credit score, so a retailer with bad credit could end up paying well above the advertised range.
The BusinessLine also carries a $95 to $175 annual fee after the first year, along with a documentation list that includes two to three years of tax returns and current financial statements — more paperwork than a newer or smaller retailer may have on hand.
3. Credibly
Credibly operates as both a direct lender and a lending partner network, depending on the product. It lends directly on working capital loans and merchant cash advances, while its business line of credit is sourced through a network of partner lenders.
That line of credit goes up to $600,000, available as either a secured or unsecured product, with repayments structured weekly or monthly depending on the offer. Approval can come back in as little as two hours, with funds arriving within four hours of that.
To qualify, a retailer generally needs a personal credit score of at least 675 and at least $20,000 in monthly revenue.
Because the line of credit is filled through partner lenders rather than underwritten by Credibly directly, the rate and terms you’re offered depend on which partner you’re matched with, so two retailers with similar profiles could see meaningfully different pricing.
It’s also worth noting that effective APRs on Credibly’s shorter-term products have also been reported well into the double and even triple digits once fees are factored in, so it’s worth reviewing the full repayment total before accepting an offer.
4. OnDeck

OnDeck is one of several online lenders that built its business around fast approvals for small businesses, offering a line of credit up to $100,000 with no draw fees or maintenance fees. Repeat draws after the first one can be issued instantly through a debit card, and OnDeck starts with a soft credit inquiry so checking eligibility doesn’t affect your credit score.
To qualify, a retailer needs at least 12 months in operation, a personal credit score of 625 or higher, and at least $100,000 in annual revenue.
OnDeck’s own disclosures show average APRs running well into the double digits, so it’s worth comparing the real cost against other lines before committing.
Because OnDeck lends directly, the rate and limit you’re offered reflect only its own underwriting, without the benefit of relationships built across multiple lenders.
OnDeck is also one of the lenders in Redline Capital’s network, so applying through us may get your retail business stronger pricing than applying directly, thanks to the volume of business we’ve sent OnDeck over the years.
5. Bluevine

Bluevine is another well-known name among online lenders, issuing business lines of credit up to $250,000 with a decision possible in as little as five minutes and funds available within 24 hours of a draw.
The line carries no fees for opening, maintaining, or paying it off early, and payments can be structured with interest-only payments during part of the term depending on the plan you select.
Qualifying generally requires a personal credit score of 625 or higher, at least 12 months in business, and monthly revenue of $10,000 or more.
Repayment terms run short, just 6 to 12 months, which pushes up the size of each payment compared to a longer amortization schedule. A personal guarantee is also required on every line, and effective APRs can run well above the headline rate once fees and the weekly repayment structure are factored in.