
It’s standard for staffing agencies to use business lines of credit to cover working capital needs like payroll, rent, or insurance while they wait on clients to pay.
The advantage of a line of credit over traditional term loans is that it’s revolving. Agencies can draw what they need, pay interest on just that amount (not the full credit line), and reuse the funds once repaid. There’s no need to apply for new financing every time an expense comes up.
But despite those benefits, who you borrow from matters, as it determines how fast and hassle-free you can close. We’ve spoken with countless borrowers who say they applied with the wrong lender and had to wait 60 to 90 days for their line of credit, just to get rejected at the last minute.
To help staffing agencies secure funding quickly, with no drama, and at low rates, we break down the five factors to consider when evaluating your financing options, then compare popular lenders.
Use our automated loan pricer to pull up instant quotes and see the terms, rates, and credit limits your staffing agency qualifies for.
5 Factors to Consider When Choosing a Business Line of Credit Lender
Factor #1: What Are Their Qualification Requirements?
Traditional lenders like banks and credit unions are extremely risk-averse, so when it comes to staffing agency financing, they set strict qualification criteria. Exact requirements vary, but you’ll typically need a 720+ credit score, a long operating history, strong profit margins, extensive cash reserves, and low debt.
One estimate puts the approval rate for small-business loans from large banks at 13.8%.
That’s why the first factor to consider is a lender’s qualification criteria. Look for options with more accessible, reasonable requirements, ones that don’t demand your business be in near-perfect financial condition.
Factor #2: Are They a Broker or a Direct Lender?
Many staffing agency owners assume that applying directly with a lender will result in better pricing, since there’s no added broker markup standing between them and the source. This logic makes sense on the surface, but it isn’t how lending relationships actually function.
Lenders adjust their pricing based on the volume and quality of applications a given source brings them. A broker who has funneled a large number of qualified applicants to a lender has effectively earned leverage that a single borrower doesn’t have.
In exchange for that consistent volume, lenders extend preferential rates, expanded credit limits, and terms that aren’t available to a one-off applicant.
This means that when you work with an established broker, you inherit the benefit of every prior deal they’ve closed with that lender, which translates into lower rates for you.
Factor #3: Do They Pressure You to Accept?
How a lender behaves after sending an offer reveals a great deal about its quality.
A lender confident in their rates has little reason to rush you. They know their numbers will hold up against the competition, so they’re willing to let you compare offers, answer your questions, and take the time you need. Strong terms don’t require urgency.
A lender with a weaker offer doesn’t have that luxury. So, they’ll follow up persistently, invent deadlines, and claim another business is waiting on the same funds, all in an effort to secure your signature before you’ve had the chance to look elsewhere.
As a general rule, the more pressure a lender puts on you, the weaker their offer tends to be.
Factor #4: How Clear and Straightforward Are the Terms?
A lender worth borrowing from lays out every relevant figure upfront, so it’s easy to understand. That means the interest rate, repayment total, term length, payment amounts, and repayment frequency.
Some line of credit providers purposefully structure their offers in ways that make comparison difficult. Burying costs across multiple fees or vague terminology isn’t an accident; it’s often designed to obscure just how much the financing actually costs.
For that reason, it’s worth prioritizing lenders who disclose their APR from the start. Since APR combines interest and applicable fees into one annualized figure, it gives you the clearest, most apples-to-apples way to compare the true cost across different lenders.
Factor #5: What Are Their Paperwork Requirements? (This Determines Your Closing Speed)
When you need a fast line of credit, it’s tempting to go with the first lender that promises same-day funding on their website.
But in reality, many lenders overpromise and underdeliver, and staffing companies find themselves in a process that drags out for weeks. As a result, we recommend against taking a lender’s promised closing speed at face value.
Instead, test their speed claims by looking at their paperwork requirements. The more documents a lender asks for, the longer it typically takes to underwrite your application and get you funded. Go with lenders who don’t ask for a mountain of documents.
5 Lines of Credit Lenders Compared
1. Redline Capital: Fast Funding at Competitive Rates
Redline Capital is a revenue-based financing company offering lines of credit to businesses across the country. Over the past decade, we’ve helped businesses that couldn’t qualify for bank financing secure hundreds of millions of dollars in lines of credit.
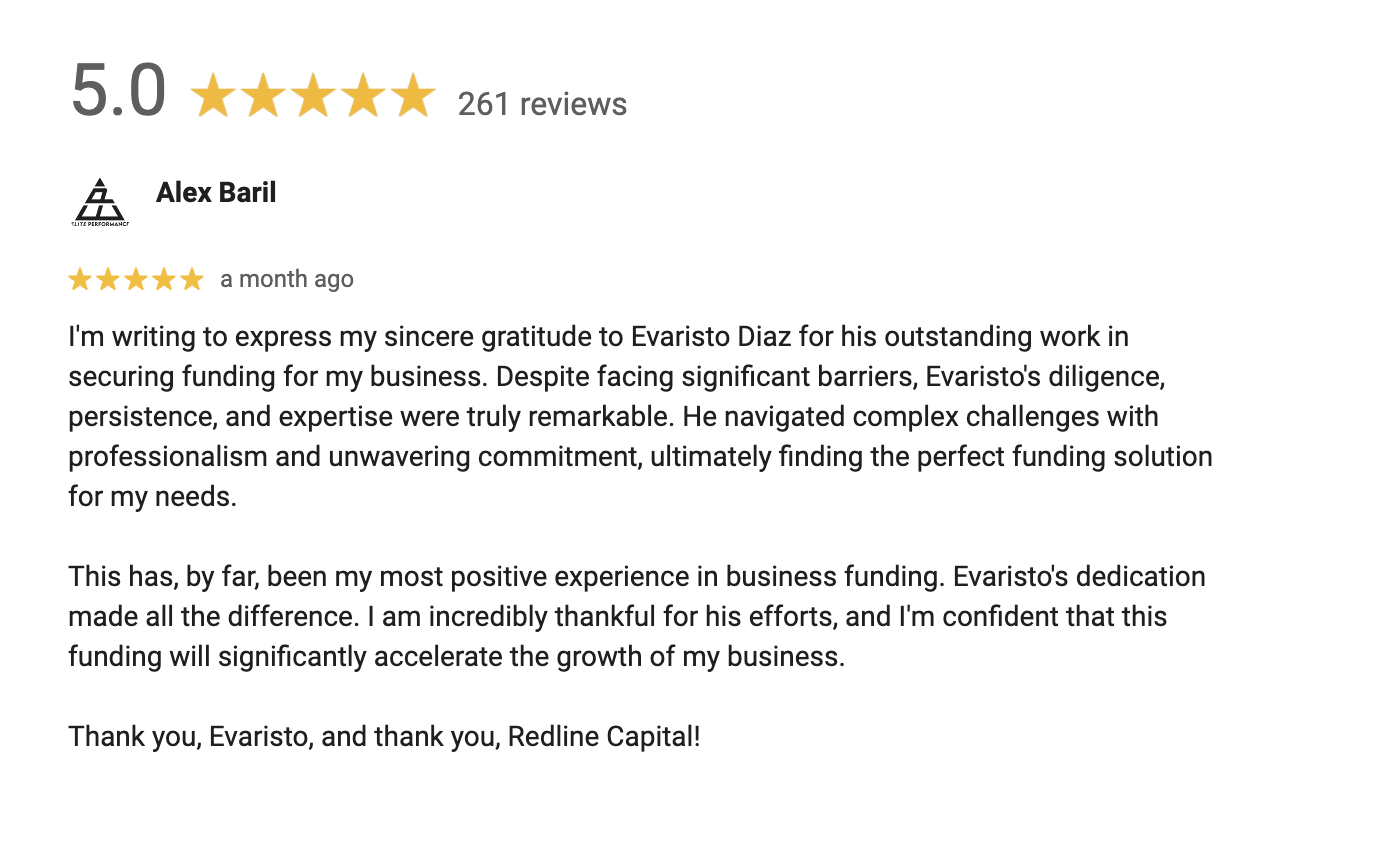
Here’s what businesses have to say about working with us:


Here’s how we satisfy the five factors above.
We Approve Over 80% of Business Applications
Our revenue-based financing model simplifies qualification down to a single number: monthly revenue. As long as your staffing agency generates at least $30,000 a month, you’re eligible. You don’t need a flawless credit profile, personal collateral, large profit margins, or extensive cash reserves.
That simplicity is why over 80% of businesses that apply with us qualify for a line of credit.
Read more: Why Use Revenue-Based Financing Instead of Debt Financing?
We Help You Secure Lower Rates Through Our Lender Relationships
Redline Capital is an established broker that has built strong relationships with top lenders over the past 10 years, including OnDeck, Headway Capital, and Rapid Finance. We’ve sent them a consistent stream of qualified applications and hundreds of millions of dollars in funded business.
That volume has earned us pricing and credit limits that those same lenders don’t extend to businesses applying on their own.
So, when you apply through Redline, you’re benefiting from the leverage we’ve built across our entire lending network. That means lower rates and higher credit limits than you’d likely secure by applying directly.
We Never Pressure You Into Accepting Offers
We don’t follow up with countdown timers, urgent calls, or claims that another business is waiting on your funding. Once we send an offer, we give you the space to review it, compare it, and ask questions, however long that takes.
We operate this way because we’re confident in the quality of our terms. We know that once businesses compare us to the competition, they normally come back to us.
Our Offers Are Easy to Understand
Every offer we send lays out the full picture upfront: your APR, repayment schedule, payment amounts, term length, and any fees.
We disclose APR on every offer specifically because it’s the easiest and clearest way to compare the real cost of financing, and we want you to be able to do exactly that.
Read more: 10 Best Payroll Financing Companies: Fast & Easy Funding
We Only Need 4 Months of Bank Statements
Because we qualify applicants based on monthly revenue, we don’t ask for years of tax returns, financial statements, or a stack of supporting documents.
All we need is four months of bank statements to verify your revenue. That’s why we’re able to consistently close lines of credit on the same day or the next day.
Secure Fast and Affordable Business Lines of Credit with Redline Capital
Use our automated loan pricer to find out the line of credit terms, rates, and credit limits your staffing agency qualifies for.
2. OnDeck

OnDeck‘s business line of credit offers up to $200,000 in revolving credit, with no annual, monthly, or draw fees. Approved businesses may receive funds as soon as the same business day. Eligible customers can also use Instant Funding to access draws of $1,000 to $10,000 through a participating business debit card.
To qualify, a staffing agency needs at least 12 months in operation, a personal credit score of 625 or higher, at least $100,000 in annual revenue, and a business checking account.
OnDeck uses a soft credit inquiry, so checking your eligibility won’t affect your credit score. However, if your credit file is restricted and must be lifted, OnDeck says the process may result in a hard pull.
That said, OnDeck’s own rate disclosures show average APRs running well into the double digits, so it’s worth comparing the actual cost against other options before committing.
Because OnDeck lends directly, the rate and credit limit offered reflect only its own underwriting, without the benefit of relationships built across multiple lenders.
OnDeck is also one of the lenders in Redline Capital’s network, so applying through us may give your staffing agency stronger pricing than applying directly, thanks to the volume of business we’ve sent OnDeck over the past decade.
Read more: Seasonal Business Financing: 6 Options for Managing Cash Flow
3. Advance Partners

Advance Partners specializes in invoice factoring for staffing agencies rather than a revolving line of credit. The company advances cash against your unpaid invoices and pairs funding with back-office support like billing and collections, working with verticals ranging from light industrial and temporary staffing to healthcare staffing agencies.
This type of payroll financing bases qualification mainly on the strength of a staffing agency’s client contract and payment history, rather than the agency’s own financials, since the accounts receivable themselves secure the advance.
Advance rates typically run up to 90% of an approved invoice’s value, sometimes up to 100% in full-service arrangements. Depending on the agreement, this kind of invoice financing can be structured as recourse or non-recourse, meaning the factoring company may or may not absorb the loss if a client ultimately fails to pay.
Because staffing agencies rarely own the kind of physical assets required for asset-based lending, accounts receivable financing tends to be the more accessible form of specialized financing for the industry.
That said, funding capacity is tied directly to eligible invoice value rather than a set credit limit. Although the cash advance can be used for operational expenses or payroll obligations, it generally can’t provide funding for work that hasn’t yet been billed. Temporary staffing agencies that want funds they can draw on for any business need, without tying availability to a specific invoice, would likely find a revolving line of credit a better structural fit.
4. Bluevine

Bluevine issues lines of credit up to $250,000 and can return a decision in as little as five minutes, with funds available within 24 hours of a draw. The line comes with no fees for opening, maintaining, or paying it off early.
Qualifying generally requires a personal credit score of 625 or higher, at least 12 months in business, and monthly revenue of $10,000 or more, thresholds a well-established temp agency can often clear more easily than a newer one.
Repayment terms run short, just 6 to 12 months, which pushes up the size of each payment compared to a longer amortization schedule. A personal guarantee is required on every line, and the product isn’t available to businesses based in Nevada, North Dakota, or South Dakota. Effective APRs can also run well above the headline rate advertised once fees and the weekly repayment structure are factored in.
Bluevine functions primarily as a direct lender for its core line of credit product, so the terms a staffing agency receives are set by Bluevine’s own criteria rather than shaped by relationships built with multiple lenders over time.
5. American Express Business Line of Credit

American Express offers a business line of credit ranging from $2,000 to $250,000, with each draw treated as its own installment loan repaid over 6, 12, 18, or 24 months. Eligible applicants can get a decision within minutes of applying.
Qualifying requires a personal credit score of at least 660, a minimum of 12 months in business, and average monthly revenue of at least $3,000.
American Express considers credit history, time in business, and other financial factors when making an approval decision and setting the credit limit, so a newer staffing agency may qualify for less funding. Initial credit limits above $150,000 are available only to select borrowers with a pre-existing Amex relationship.
The product also requires a personal guarantee, and pricing is based on the business’s overall financial profile, making it harder to estimate your exact cost before applying.
Funds drawn from the line of credit can be deposited within seconds into an Amex Business Checking account, while transfers to another bank generally take one to three business days. Applications that can’t be automatically verified may take longer to review.