
Washington businesses often need to cover short-term expenses or capitalize on opportunities (e.g., payroll, restocking inventory, a bulk discount, a piece of equipment) before they have the cash on hand. A business line of credit solves that by giving businesses access to revolving, flexible financing they can use whenever they need capital.
You draw only what you need, pay interest on that amount, and once you repay it, the credit is available to use again. You don’t have to reapply every time you need more funds, as you would with a term loan.
That said, who you borrow from makes a real difference because it affects how easy it is to qualify, how fast you get funded, and how much interest you end up paying. Here’s what we recommend checking before you apply.
- Start with the lender’s requirements. Many lenders set a high bar (e.g., perfect credit, years in business, personal guarantees, strong cash flow), which automatically disqualifies many businesses. A lender with more realistic criteria gives you an actual shot at qualifying.
- Don’t rely on a lender’s advertised funding speed. Plenty of lenders promise a fast turnaround on their website, but take much longer to fund. Rather than relying on a lender’s promises, check their paperwork requirements, as it’s a better way to judge speed. The more a lender asks for, the longer they normally take to fund.
- Watch how a lender behaves after sending an offer. Steer clear of lenders that pressure you to sign fast, because it’s usually a sign of an expensive offer. They are trying to keep you from finding better offers. Choose low-pressure lenders, since a lack of pressure usually reflects stronger pricing.
- Check the credit limit you qualify for. Many lenders are highly risk-averse and only extend small credit limits, which can mean qualifying for a line of credit that still isn’t enough to handle the expense you actually need it for.
Most line of credit lenders don’t meet all four of these criteria. Banks and credit unions, for example, offer some of the lowest APR rates, but they take a long time to fund and are difficult to qualify for. Alternative lenders fund faster and have more accessible criteria, but charge higher interest rates.
So, we put this guide together to help Washington businesses qualify faster, avoid unnecessary delays, and get the best rate available to them.
Run your numbers through our loan calculator for an instant look at the rates, terms, and credit limits your business qualifies for.
1. Redline Capital: Fast and Affordable Revenue-based Lines of Credit
We founded Redline Capital because we saw many businesses applying for a line of credit at a bank only to end up getting rejected.
Banks have such strict, borderline unrealistic requirements that they only approve around 13% of businesses. This leaves a large percentage of businesses without the working capital they need to operate.
At Redline, we serve that overlooked share of the market. We made our qualification criteria more realistic, so businesses can secure the financing they need quickly.
We work with Washington businesses across a wide range of industries, including:
- Restaurants and retailers
- Medical and dental practices
- Staffing agencies
- Construction companies
- Security companies
- HVAC businesses
- Auto repair shops
- Law firms and consultants
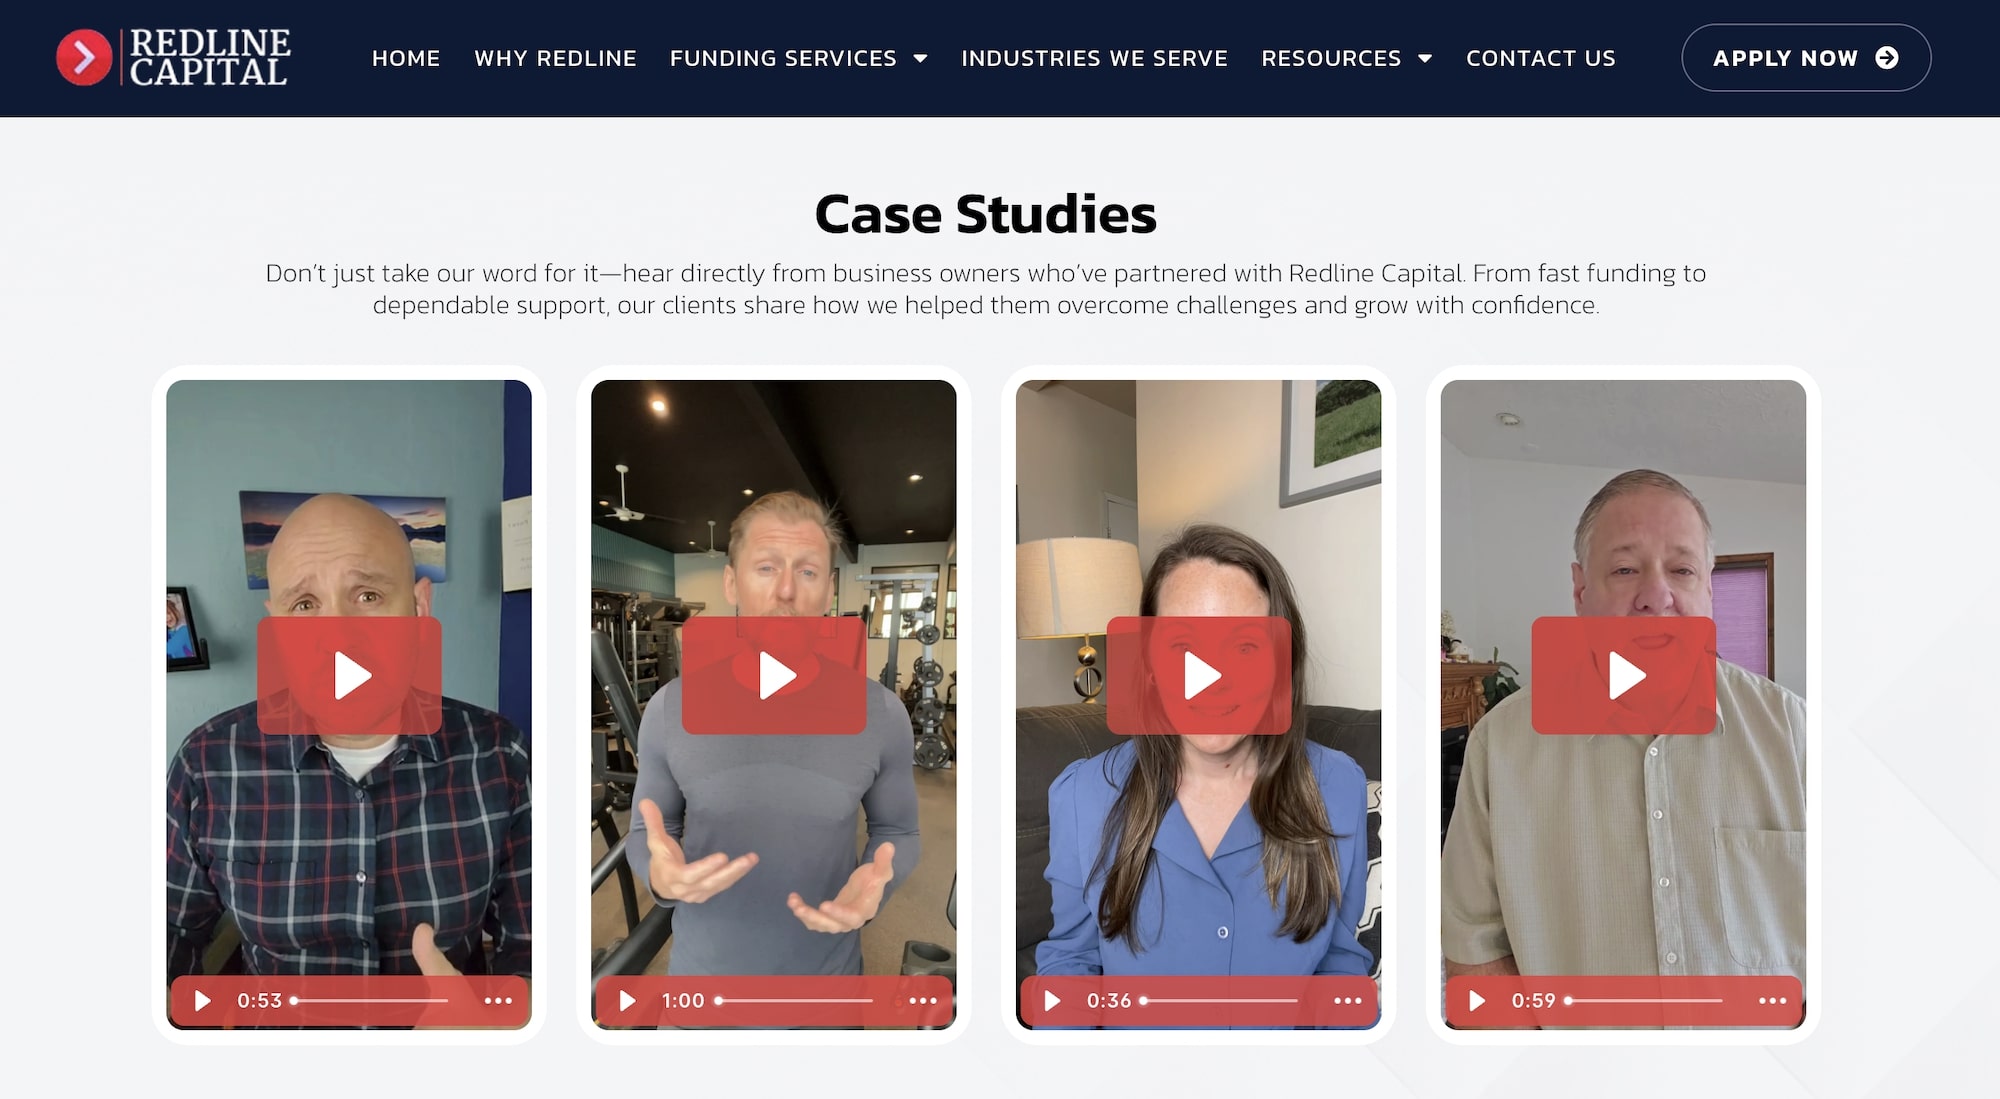
Here’s what Washington businesses say about our line of credit product:


Check out our case studies page to hear directly from borrowers about their experience:
Below, we explain how we designed Redline Capital to satisfy the criteria above.
Our Qualification Criteria Are Accessible; We Approve 80%+ of Businesses
As we mentioned, most lenders have requirements that can be tough and sometimes borderline impossible to clear. That’s exactly why it’s worth checking a lender’s criteria before you commit, so you’re not weeks into an application only to get rejected. That wastes time you could’ve spent applying somewhere more realistic from the start.
With Redline, qualifying comes down to three things:
- $30,000 or more in monthly revenue
- At least 12 months in operation
- Being based in the U.S.
We don’t require a credit score, collateral, a personal guarantee, two years of tax returns, or a debt schedule. That’s why we’re able to approve more than 80% of the businesses that apply.
We Just Need 4 Months of Bank Statements and Can Close the Same Day You Apply
Don’t take a lender’s advertised closing speed at face value. We hear from borrowers all the time about how a lender they partnered with promised to close the same day but then took multiple weeks.
Paperwork requirements are a better indicator of speed. The more documents a lender asks for, the longer it takes to review your application, and the longer you’ll wait for a decision.
At Redline, we only need four months of bank statements to verify your revenue. That’s it, no tax returns, business plans, collateral appraisals, or years of financials to track down and underwrite. This lets us close most small business loans the same day you apply.
We Never Pressure You Into Accepting an Offer
From our experience, if a lender pushes you to accept quickly, that’s usually a sign the offer is expensive. They don’t want you comparing it elsewhere and finding something cheaper.
You won’t run into that with us. We’re confident in our pricing because of the relationships we’ve built with top lenders, ones we’ve sent a steady volume of business to over the years (e.g., OnDeck, Rapid Finance, Headway Capital, Credibly). In return, they offer our applicants better rates and repayment terms than a business would get applying on its own.
We actually test this ourselves. We check rates from our lending partners, then ask businesses to send over what they were offered directly from that same lender. Our pricing almost always comes out lower.
We Extend Larger Credit Limits Than Most Lenders
Most banks and lenders keep credit limits thin, often just 10% to 30% of your monthly revenue. That can mean qualifying for a line of credit that still isn’t enough to settle most expenses like inventory, rent, or payroll.
We go further. Because we’re not weighing your credit score, collateral, or profit margins, we can extend credit lines up to $750,000, or as much as 200% of your monthly revenue.
See What You Qualify For with Redline Capital and Get Funded As Quickly as Today or Tomorrow
Enter a few details about your business into our automated loan calculator for instant quotes on the rates, terms, and credit limits you’re eligible for.
Alternative Line of Credit Lenders to Consider in Washington
WaFd Bank
WaFd Bank is a full-service bank headquartered in Seattle, offering a range of small business loans and credit products alongside its Express Business Revolving Line of Credit. That line comes with interest-only payments for up to five years, and businesses can also apply for a revolving SBA-backed line of credit through WaFd’s status as an SBA preferred lender.
To qualify for the Express line, WaFd generally wants a guarantor with a credit score of 680 or higher, at least three years in business, and a WaFd business deposit account set up for automatic payments. Unsecured amounts go up to $50,000, while secured lines can reach $100,000.
That three-year minimum shuts out newer businesses regardless of how strong their current revenue looks, and requiring a WaFd deposit account with automatic payments means you’re committing to a broader banking relationship just to access the credit line itself.
BECU
BECU is a credit union open to anyone who lives, works, worships, or attends school in Washington, along with residents of select counties in Oregon and Idaho. Its business line of credit can be linked to a business checking account for overdraft protection, and funds transfer out in $100 increments as needed.
To qualify, a business must first become a BECU member by opening a Business Member Share savings account, and it must be registered with the Washington, Oregon, or Idaho Secretary of State, or with the Washington Department of Revenue.
BECU’s business line of credit tops out at $49,999, a real ceiling for a business that needs more than that to cover payroll or restock inventory during a busy stretch. Membership itself is also a prerequisite step that adds time before you can even apply for the credit line.
OnDeck

OnDeck is a direct lender that built its business around fast approvals for small businesses, offering a line of credit up to $100,000 with no draw fees or maintenance fees. Repeat draws after the first one can be issued instantly through a debit card, and OnDeck starts with a soft credit inquiry so checking eligibility doesn’t affect your credit score.
To qualify, a business needs at least 12 months in operation, a personal credit score of 625 or higher, and at least $100,000 in annual revenue.
OnDeck’s own disclosures show average APRs running well into the double digits, so it’s worth comparing the real cost against other lines before committing.
Because OnDeck lends directly, the rate and limit you’re offered reflect only its own underwriting, without the benefit of relationships built across multiple lenders. OnDeck is also one of the lenders in Redline Capital’s network, so applying through us may get your business stronger pricing than applying directly, thanks to the volume of business we’ve sent OnDeck over the years.
Rapid Finance

Rapid Finance is an online lender that has funded small businesses since 2005, offering a line of credit up to $250,000 alongside a broader menu of term loans, SBA loans, and asset-based financing. Approved businesses can often get a decision the same day, with funds arriving within a single business day.
Eligibility depends on the product, but a line of credit generally calls for a credit score in the 550 to 600 range, along with steady monthly revenue and some operating history.
Rapid Finance performs a hard credit pull rather than offering a soft check upfront, so comparing your options here comes with a mark on your credit report. The company also doesn’t publish specific rates or a minimum revenue threshold for its line of credit, which makes it harder to know where you stand before applying.
Rapid Finance is another lender in Redline Capital’s network, so applying through us may secure your business better pricing than going to Rapid Finance directly.