
California is home to millions of small businesses, and many of them lean on a line of credit at some point to bridge the gap between money going out and coming in.
Unlike a term loan, which hands you a fixed sum you start repaying right away, a line of credit only charges you for what you actually use. Repay it, and the credit becomes available again with no new application required.
That much is true regardless of who you borrow from. But the lender you choose determines how fast you close, what you end up paying, and how demanding the approval process is.
So, before committing to a lender, here are a few things worth checking:
- Look into what it actually takes to qualify. Banks typically want great credit, margins, cash reserves, and collateral, leaving most businesses unable to qualify. All of those criteria also take time to verify, which is why funding often stretches to 60 or 90 days. A lender with simpler criteria gets you approved more easily and funded faster.
- Notice how a lender behaves once an offer is on the table. One that’s confident in its pricing won’t rush your decision; it’ll let you sit with the offer, compare it elsewhere, and come back on your own schedule. A lender pressuring you to sign quickly is usually a sign their offer can’t hold up to scrutiny.
- Confirm the lender can actually lend in your region. California has over 275 credit unions, and most restrict membership to a specific handful of counties, meaning a credit union built for the Bay Area may have no path to membership for a business in San Diego, for example. Check their service area before you apply.
We put together this guide to help California businesses figure out which lenders are actually worth their time, then compare the state’s top options.
Our automated pricer lets you generate instant quotes and see the rates, terms, and credit limits your business qualifies for.
1. Redline Capital: Same-day Lines of Credit at Competitive Rates for California Businesses
Over the past 10 years, we’ve funded lines of credit for all kinds of California businesses, including restaurants, retailers, construction companies, doctors’ offices, and more. We position ourselves as an alternative to banks, credit unions, and traditional online lenders that ask for far more than most growing businesses can offer.
Because of our simple qualification criteria and lightweight paperwork requirements, we have approval rates north of 80% and funding available the same day you accept an offer.
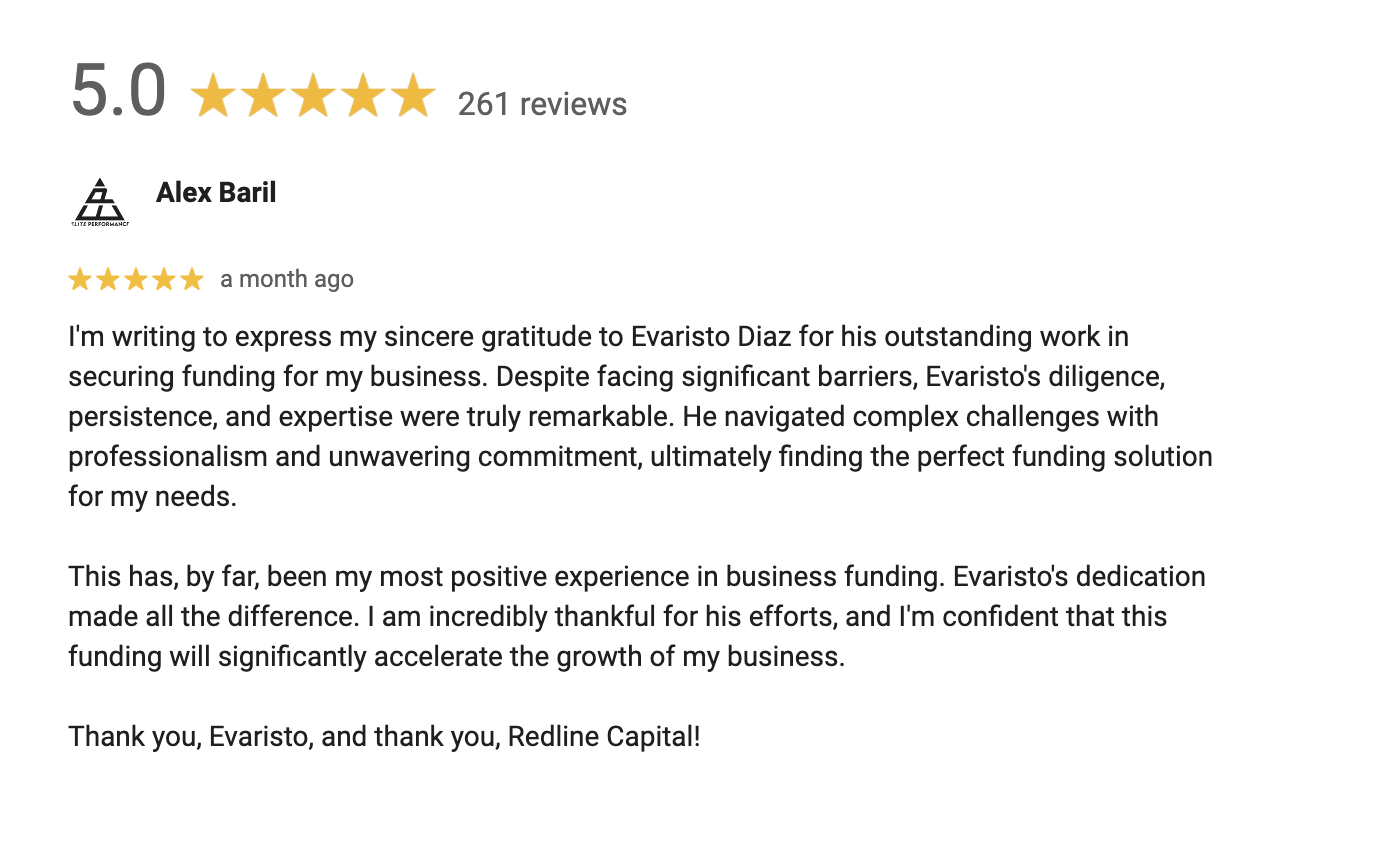
See what California businesses have to say about working with us:


We’re Easier to Qualify With and Faster to Fund Than a Bank
As a revenue-based financing company, Redline Capital evaluates your line of credit application mainly on the amount of revenue you generate. Your business credit score, profit margins, cash reserves, debt-to-income ratios, or collateral don’t matter to us the way they would to a regular bank or credit union.
As long as your business brings in $30,000 or more each month, has at least a year of time in business, and operates within the U.S., you stand a strong chance of getting approved. In fact, more than 80% of the businesses that apply with us qualify.
Compare that to a bank, where fewer than 1 in 7 applicants actually gets approved.
That simplicity carries over to funding speed, too. By skipping collateral appraisals, years of tax returns, and other paperwork banks require, we have far less to review. That’s why we can send you an offer within hours and have funds in your account before the day is over.
Read more: Why Use Revenue-Based Financing Instead of Debt Financing?
We Allow You to Secure the Best Rates Available to Your Business
A lender who pressures you into accepting their offer with nonstop calls and emails is telling you something. It usually means they know their offer is expensive and want to lock you in before you find something better.
That’s not how we operate. We’re proud of the quality of our offers and actually encourage businesses to shop around and see for themselves. There’s no pressure to accept.
We can help businesses secure the best rates available to them because we’re a broker with 10+ years of relationships with OnDeck, Rapid Finance, Headway Capital, and other top lenders. We’ve sent them hundreds of millions of dollars in business, and in return, they offer our applicants exclusive APRs and larger credit limits.
So, when you apply through Redline, you inherit the benefit of every deal we’ve closed with these lenders before yours.This is leverage no business could build on its own with a single application.
We Can Work With Businesses Anywhere in California
Most California credit unions only accept members from a handful of counties, so a business in Sacramento might not qualify for one built around the Bay Area, no matter how strong its financials look.
We don’t draw those lines. Whether you’re in San Diego, San Francisco, Fresno, or a small town in between, we work with businesses no matter where in the state they’re based.
Secure a Fast Business Line of Credit for Your California Business with Redline Capital
Enter a few details about your California business into our automated pricer and generate instant quotes detailing your rates, terms, and credit limits.
2. California Bank & Trust

A division of Zions Bancorporation, California Bank & Trust structures its business line of credit around short-term working capital needs, and businesses can link the line to a business checking account for overdraft protection.
Beyond the standard relationship-driven process, the bank also offers a streamlined digital option called Business Access, which can return same-day decisions and expedited funding for smaller credit requests. As an SBA loans Preferred Lender, it also handles 7(a) and 504 loans in-house for businesses that need longer-term, government-backed financing, including options built around financing commercial real estate.
Qualifying for most of the bank’s lending products generally requires a credit score of at least 650 and a minimum of two years in business.
That two-year requirement shuts out newer businesses regardless of how strong their current revenue looks. Some borrowers have also reported paying higher rates on certain CB&T products compared to other lenders, which is something to consider when you’re weighing multiple offers side by side.
Read more: 10 Best Same-Day Merchant Cash Advance Providers
3. Banc of California

Banc of California builds its business lending around a relationship model, pairing each business with a dedicated banker who can offer personalized guidance rather than a one-size-fits-all process. As part of that process, newer applicants may also be asked for a business plan outlining how the funds will be used.
Its revolving secured lines of credit are usually backed by business or personal assets, and the bank also holds preferred status with the Small Business Administration, helping businesses navigate 7(a) and 504 loan programs for larger, longer-term financing needs.
Because Banc of California doesn’t publish a fixed set of credit or revenue thresholds, every application is subject to credit approval through a relationship manager, so a business has to work directly with a banker to find out where it stands.
That collateral requirement is the bigger limitation here. A business without real estate, equipment, or other qualifying assets to pledge won’t have access to this line of credit at all, regardless of how healthy its cash flow looks.
4. Monterra Credit Union

Monterra Credit Union, based in the Bay Area, offers a revolving business line of credit alongside a business credit card with rewards (worth checking closely if an annual fee applies before you sign up), and smaller credit requests can be handled through a fully digital application. Businesses can also open a business checking or savings account online without a branch visit to get started.
To qualify, you first have to join Monterra as a member. Membership is limited to businesses and individuals who live, work, worship, or attend school in San Mateo, Alameda, Contra Costa, Santa Clara, or San Francisco County, along with employees of partner organizations and family members of existing members.
That five-county footprint rules out a business based anywhere else in California, including Los Angeles, San Diego, Sacramento, or the Central Valley, no matter how strong its finances are. Membership also has to be established first, through opening a share account, before a line of credit application can even begin.
5. Kapitus

Kapitus, a direct lender founded in 2006, offers a business line of credit alongside a broader menu of products, including term loans, equipment financing, and invoice factoring. Its initial eligibility check runs on a soft FICO score pull, so comparing offers doesn’t affect your credit score. Approved businesses often see a decision in about four hours, with funds arriving as soon as the next day.
Through its KapitusPLUS process, Kapitus can also surface multiple loan offers from different lending partners, each with its own repayment terms and possible origination fee, for a business to compare side by side.
Qualifying for its core business line of credit generally requires a credit score of at least 650, a minimum of two years in business, and around $250,000 in annual revenue.
That combination of requirements puts Kapitus out of reach for newer businesses and smaller operations without an established revenue history, even ones with strong current cash flow. A business that doesn’t clear all three thresholds at once won’t qualify for this product, regardless of how it performs on any single measure.
Frequently Asked Questions
How difficult is it to get a business line of credit?
It depends on the lender. Banks in California typically approve only a small share of applicants, often requiring near-perfect credit, at least two years in business, and strong financials. That’s why many businesses turn to revenue-based financing instead, since it’s far easier to qualify for when revenue is what matters most.
Can my LLC get a line of credit?
Yes. LLCs and sole proprietors are eligible for a business line of credit at virtually every bank, credit union, and alternative lender, provided the business meets that lender’s requirements. You’ll typically need an EIN, business formation documents, and sometimes a personal guarantee to qualify.
Who qualifies for a business line of credit?
Qualification varies by lender, but most look at your operating time, revenue, and credit history. Banks set the highest bar, often requiring two or more years in operation and 720+ credit. Revenue-based lenders focus mainly on monthly revenue, making qualification more accessible.
What can you use a business line of credit for?
Common uses include covering payroll or cash flow gaps while waiting on accounts receivable to clear, stocking up on seasonal inventory, capturing early-payment supplier discounts, and handling unexpected expenses. It’s best suited for short-term, recurring needs rather than long-term investments.
What are some eligible uses of the Small Business Loan Guarantee program financing proceeds?
You can use the funds for start-up costs, construction, equipment purchases, inventory, working capital, business expansion, agriculture, and lines of credit. Proceeds must be used to operate a business within California, and the program can guarantee up to 80% of the loan, capped at $1 million.
How does a business line of credit differ from a term loan or cash advance?
A term loan gives you a lump sum upfront that you repay on a fixed schedule, with interest accruing on the full amount immediately. A cash advance is repaid against future sales rather than fixed installments. A line of credit lets you draw only what you need, repay it, and borrow again, paying interest solely on what you use.
How do I increase my business line of credit limit?
Most lenders review your account periodically and may raise your limit if your revenue grows, you maintain a strong repayment history, and you don’t consistently max out the line. You can also request an increase directly, though approval typically requires updated financials.
What are the best banks in California for obtaining a business line of credit?
It depends on your business’s financial profile. Established businesses with strong credit may do well with California Bank & Trust, Banc of California, or a national bank like Bank of America. Newer or smaller businesses often have better luck with a revenue-based lender like Redline Capital, which approves over 80% of applicants.
What are the interest rates for a business line of credit in California?
Rates vary widely by lender and borrower profile. Bank lines are typically tied to the prime rate plus a margin, often landing in the high single digits to upper teens. Online and alternative lenders can start lower but often run higher overall once fees are factored in.