
It’s normal for Massachusetts businesses to lean on lines of credit to manage cash flow and cover short-term expenses while waiting for sales to come in.
Unlike term loans, a line of credit is revolving: you draw only what you need, pay interest on that amount, and once you repay it, the credit is available to use again. You don’t have to apply again each time a new expense arises.
Those benefits aside, where you get a line of credit affects how easy it is to qualify, how fast you get funded, and what interest rates you end up paying. Banks, credit unions, and private lenders all approach lines of credit differently, so here are four factors to consider before choosing a lender:
- What are their requirements? Many lenders set extremely tough criteria (e.g., strong credit history, years in business, low debt, personal guarantees), so most businesses don’t qualify. What’s worse, you often don’t find out you’ve been rejected until weeks into the application process. That wastes time you could’ve spent applying somewhere more realistic. Choose a lender with realistic requirements from the start.
- How much paperwork do they need? Many lenders promise fast funding on their homepage but rarely deliver. If speed is a priority, we suggest checking a lender’s paperwork requirements instead, since they’re a better indicator of speed. The more documents a lender asks for, the longer you can expect to wait for your funds.
- Does the lender pressure you into signing their offer? Pressure to sign quickly can keep you from comparing options and finding a better deal. Choose a lender that gives you time to review the terms and compare offers without pressuring you to sign.
- What are the lender’s credit limits? Some Massachusetts lenders cap their entry-level lines at $10,000 to $25,000, which may not cover larger expenses such as payroll or a major equipment purchase. Look for a lender willing to extend a loan amount that matches what you actually need.
We put this guide together to help Massachusetts businesses qualify faster, get funded without unnecessary delays, and secure the best available rates.
We’ll start with ourselves at Redline Capital, where we designed our lending process to help businesses qualify easily, get funded the same day, and secure lower rates than they’d find elsewhere.
Run your numbers through our loan calculator for an instant look at the rates, terms, and credit limits your business qualifies for.
1. Redline Capital: Qualify Easily, Get Funded Fast, and Secure Low Rates
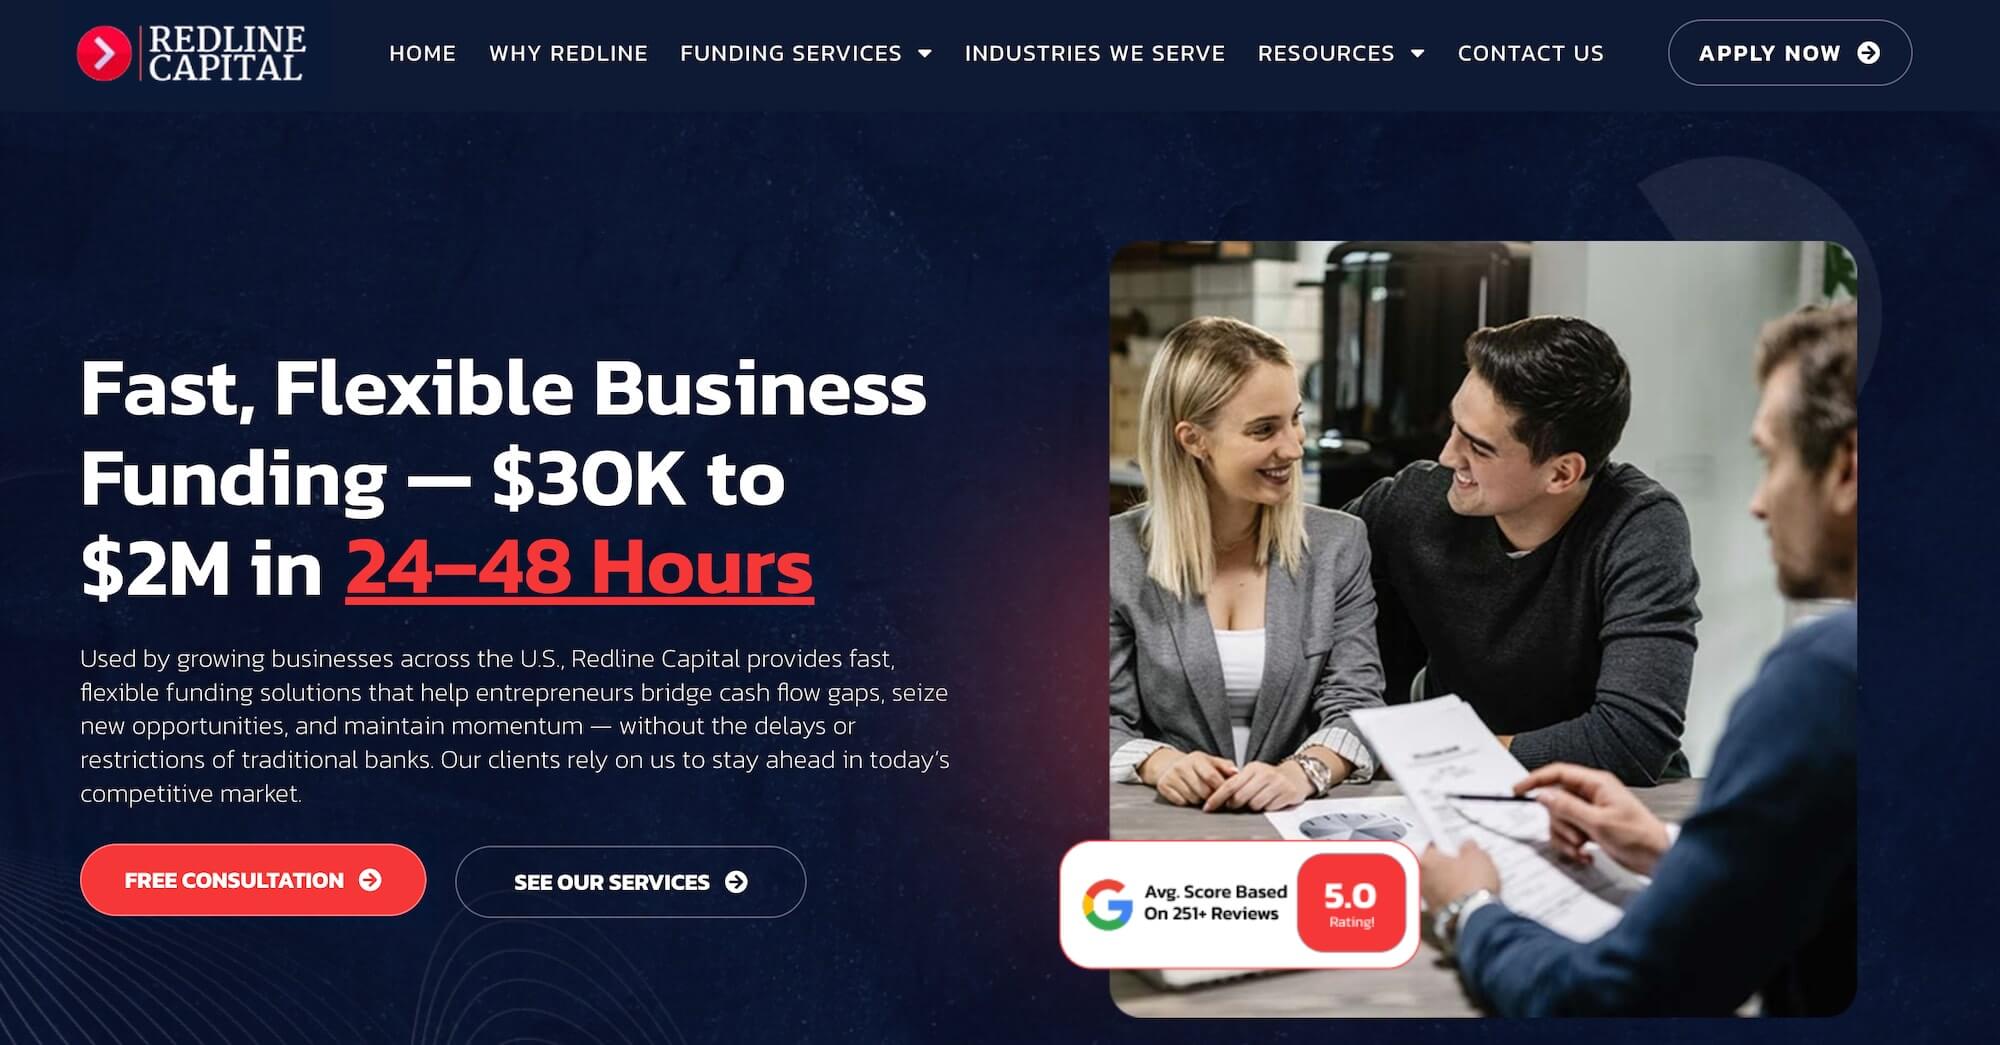
Redline Capital is a revenue-based financing company built around a simple idea: a business shouldn’t have to be in near-perfect financial shape to get a line of credit or small business loan.
We designed our process to remove the strict requirements and long delays that shut most businesses out at a bank, and to make qualifying, funding, and pricing as simple as possible.
We work with businesses across a wide range of industries, including:
- Restaurants and retailers
- Medical and dental practices
- Staffing agencies
- Construction companies
- Security companies
- HVAC businesses
- Auto repair shops
- Law firms and consultants
- And more


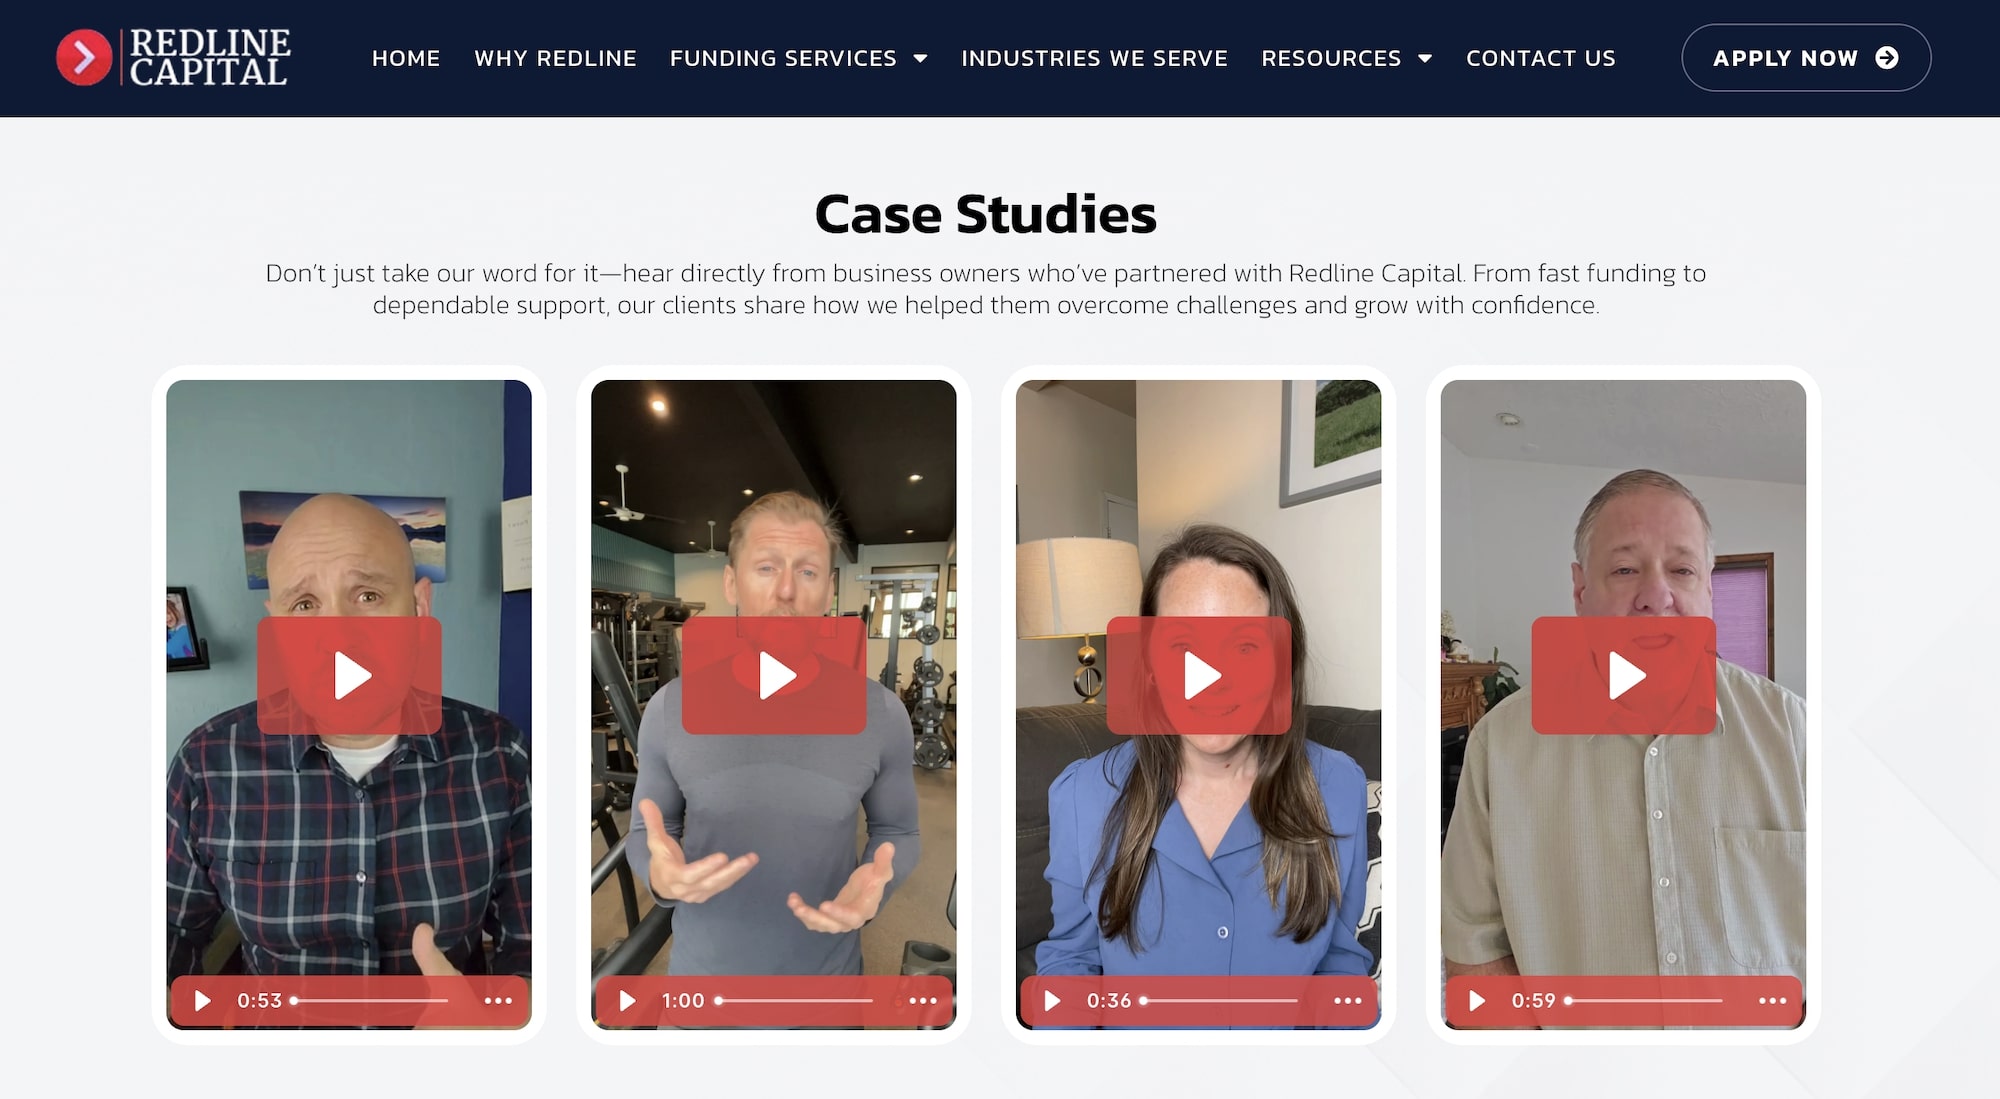
Browse our case studies page to hear borrowers describe what it was like to work with Redline Capital:
Our Qualification Requirements Are Simple, and We Approve Over 80% of Applicants
As we noted earlier, banks and credit unions reject the majority of businesses that apply for a line of credit, and you often don’t find out until weeks into the process. By then, you have to start over with another lender, and you may have already missed a deadline.
We built Redline around simpler criteria. Qualifying comes down to three things:
- $30,000 or more in monthly revenue
- At least 12 months in operation
- Being based in the U.S.
That’s it. We don’t require a strong credit history, a profit margin threshold, or collateral. Because our bar is so much lower than a bank’s, we approve more than 80% of the businesses that apply.
Read more: How to Use a Business Line of Credit: Smart Uses & Mistakes
We Only Ask for 4 Months of Bank Statements to Confirm Your Monthly Revenue
Many lenders overpromise on closing speed in their advertising and simply don’t deliver. This is another reason lines of credit take so long to close, and why businesses end up missing important deadlines.
Instead of taking a lender’s promises at face value, check their paperwork requirements. They are a far more reliable proxy for actual speed. The more documents a lender asks for, the more time they spend underwriting and evaluating everything you submit, and the longer you wait as a result.
At Redline, we close most lines of credit the same day or the next. That’s because we only need to evaluate four months of bank statements confirming you bring in $30,000 or more a month. Unlike traditional bank loans, you won’t need to gather tax returns, financial statements, a business plan, collateral documentation, or years of profit and loss history.
We Offer Some of the Best Rates in the Industry
We don’t rely on repeated calls or manufactured deadlines to secure your signature like many lenders do, because we trust our pricing to speak for itself. There’s no pressure to accept, and you can take as long as you need to compare our offer elsewhere.
That confidence comes from being an established broker. Over the past decade, we’ve built relationships with top business lenders, including OnDeck, Headway Capital, and Rapid Finance, and sent them hundreds of millions of dollars in qualified business. In return, they extend our applicants interest rates and repayment terms a business wouldn’t receive applying directly.
We Extend Larger Credit Limits Than Most Lenders
Some Massachusetts banks cap their entry-level lines at $10,000 to $25,000, which rarely covers payroll, a large inventory order, or an unexpected repair. A bigger loan amount is usually reserved for businesses with near-perfect financials and collateral.
We take a different approach. Because we’re not weighing your credit score, collateral, or profit margins, we can extend credit lines up to $750,000, or as much as 200% of your monthly revenue. That gives you room to fund business growth, not just cover this month’s bills.
Check Your Line of Credit Limit and Rate Before You Apply
Enter a few details into our loan pricer to preview the limit, rate, and terms you could qualify for, then send four months of bank statements to receive offers as early as the same day.
Other Massachusetts Lenders to Consider
We always encourage comparing options before you commit, so here are six additional lenders serving Massachusetts and how they measure up on requirements, process, and credit limits.
2. Country Bank
Based in Massachusetts, Country Bank positions commercial lines of credit as one of its strengths. Its Business Express line of credit is built to supplement working capital, finance inventory, and offset seasonal swings in cash flow, and it carries no application, annual, or documentation fees.
The bank also writes SBA loans backed by the Small Business Administration. Its Business Express Term Loan covers equipment financing for new or used machinery and leasehold improvements, and larger businesses can work with its commercial lenders on commercial loans beyond the Business Express limits.
Country Bank’s recent Business Express promotions have required at least two years in business and a credit score of 700 or higher. Applicants have also had to apply in person at one of its banking centers.
The Business Express line tops out at $25,000, a loan amount that can fall short of payroll or inventory needs for a growing business. Anything larger moves to the bank’s separate commercial line of credit, which you arrange through a commercial lender.
3. Middlesex Savings Bank
Middlesex Savings Bank has provided financial services to individuals, families, and business owners across Massachusetts. Its business line of credit goes up to $1.5 million, and a separate Business Reserve Line of Credit protects against overdrafts, supplements seasonal cash flow, and funds small purchases.
The bank is an SBA Preferred Lender, so it also makes SBA loans, and it offers a business term loan, a Business Line-to-Loan hybrid, and a business mortgage. For everyday banking, it offers business checking accounts and business credit cards.
Middlesex states that all offers of credit are subject to approval and does not list a fixed credit score or time in business minimum for its lines. The quickest way to find out where you stand is to talk with its business lending team.
The Business Reserve line stops at $10,000, which suits overdraft cover and small purchases better than payroll or inventory orders. The full business line has far more room, but the process starts with a conversation with a business banker, so you will likely wait longer for a decision than you would with an online lender.
4. Rockland Trust
Rockland Trust serves businesses across Massachusetts and Rhode Island, and the bank says its goal is easier access to capital for small businesses. Its business line of credit is revolving, with advances by check, by phone, or online, and payments automatically debited from a Rockland Trust business account earn a 0.50% savings.
As an SBA Preferred Lender, Rockland Trust makes SBA 504 loans and 7(a) loans to help fund business growth, and the Small Business Administration named it the top 504 third party lender in Massachusetts for 2023. The bank also offers fixed-rate term loans with terms up to 84 months, a commercial mortgage, merchant services, and business checking accounts.
Secured lines run from $10,000 to $750,000, and unsecured lines go up to $100,000 for qualified applicants. The bank states that SBA products are subject to SBA eligibility requirements and credit approval, and it does not list a minimum credit score for its lines.
Reaching the top of the range means pledging collateral, because unsecured lines stop at $100,000. That adds a step before funding, and you work through a local banker rather than a self-serve online form.
5. Eastern Bank
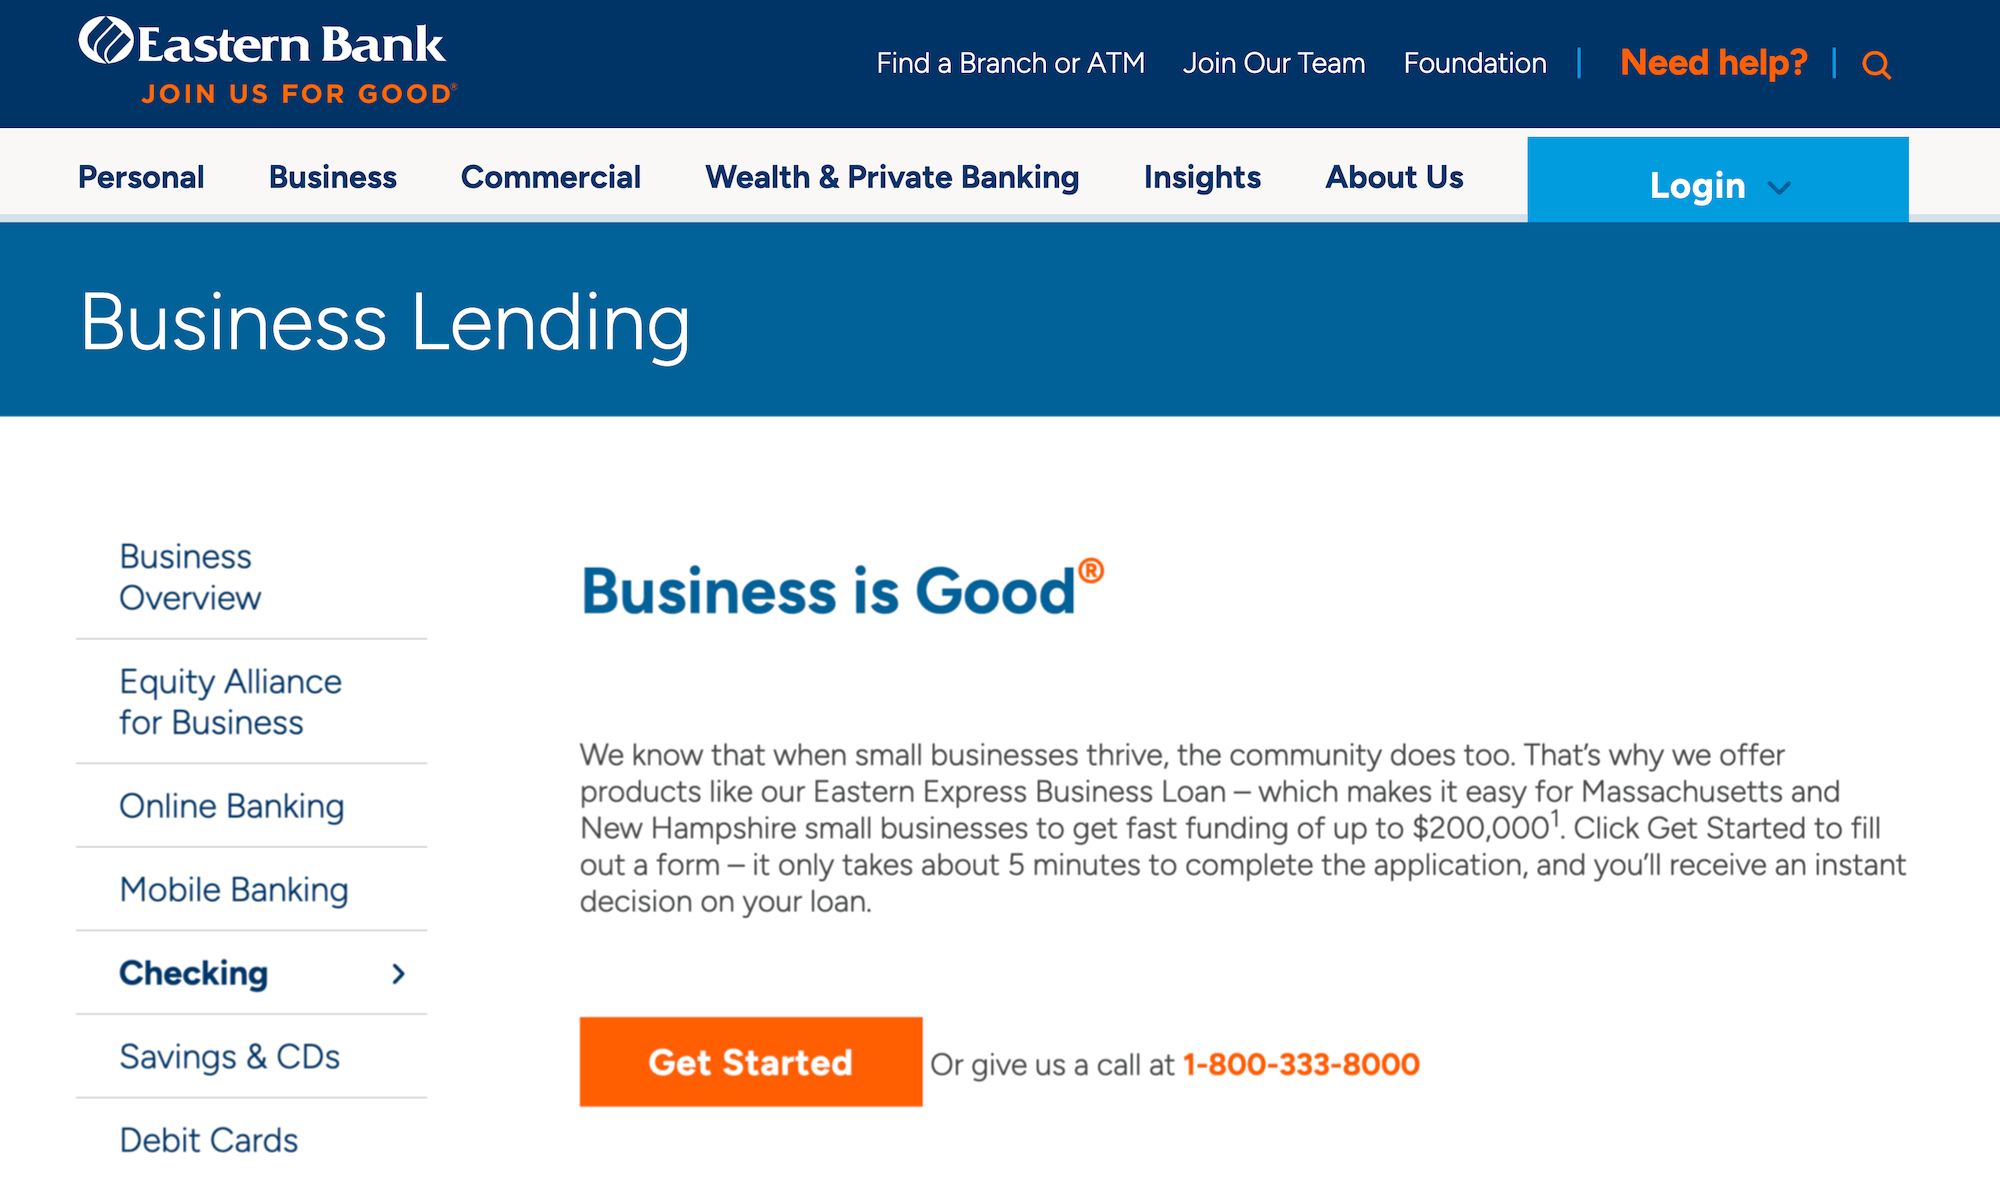
Eastern Bank is headquartered in Boston, runs more than 90 branches, and calls itself Massachusetts’ #1 SBA lender. Its financial services for business owners include lines of credit up to and over $100,000, cash management, merchant services, and loans to buy, refinance, or improve commercial property.
Borrowers can use an Eastern line of credit for renovations, equipment, working capital, seasonal cash flow, or inventory. For financing over $200,000, the bank points to its Business Term Loan, and it also offers business credit cards.
In 2023, Eastern launched a special purpose credit program that removes the minimum credit score on small business loans up to $100,000 for businesses referred by community organizations after they complete technical assistance or training. Businesses without a referral still apply through the standard process, and requests over $100,000 go through a regional lender.
Eastern also has a Ready Cash line for businesses without enough assets to collateralize a line, which uses a second mortgage on your primary residence as a backup source of repayment. That puts your home behind the line, a real risk for small business owners who want to keep personal property out of the deal.
6. Credibly
Credibly was founded in 2010 as RetailCapital and offers working capital loans and merchant cash advances alongside its business line of credit. The line runs from $5,000 to $300,000, with repayment terms of 3 to 24 months and payments made weekly or monthly.
To qualify, Credibly asks for at least six months in business, $20,000 or more in monthly revenue (about $240,000 in annual revenue), and a business bank account, and it says its line of credit partners accept applications starting at a 700 credit score. Consistent monthly deposits, verified through bank statements, are a primary factor in its underwriting.
Credibly quotes interest as a monthly rate of 3% to 5%, which works out to a much higher annual cost than a bank line, so compare the total repayment before you accept. The credit score and revenue requirements are also steeper than those for its working capital loans, which makes the line harder to qualify for than its other products.
Credibly also works with Redline Capital as a lending partner, so applying through us may secure your business better pricing than going to Credibly on your own, based on the volume of business we’ve sent its way.
7. OnDeck
OnDeck is a direct online lender built around fast decisions for small businesses. Its line of credit goes up to $100,000, carries no draw fees or maintenance fees, and sends repeat draws instantly through a debit card.
To qualify, OnDeck asks for at least 12 months in business, a personal credit score of 625 or higher, and annual revenue of $100,000 or more. Checking your eligibility starts with a soft credit inquiry, so it does not affect your score.
OnDeck’s average APRs run well into the double digits, so compare the true cost against other lines before you accept. Because OnDeck lends directly, you see one lender’s view of your business rather than offers from several.
OnDeck is also a lender in Redline Capital’s network. Applying through us may get your business better interest rates than applying directly, based on the volume of business we’ve sent OnDeck over the years.