
It’s common for healthy auto shops to run into cash flow gaps, because parts, technician wages, and other operating expenses are due before the repair is paid for, and fleet and insurance-paid jobs can take weeks longer. A line of credit helps bridge this gap by giving auto shops access to a fixed amount of capital that they can draw from whenever they need.
The advantage of lines of credit over regular business loans is that you only pay interest on the amount you withdraw, not the entire balance, and once you repay, you can start using it again. There’s no need to reapply for a new business loan each time a new expense comes up.
Despite these benefits, what we see is that many businesses don’t put enough thought into choosing their lender. The lender you pick makes a big difference, because lenders vary widely in how hard they are to qualify with, how long they take to fund, and what they charge in interest rates and fees.
To help auto shops get funded quickly, at a fair price, and without drama, we cover the questions that separate high-quality lenders from low-quality ones and then compare the best business lines of credit side by side.
Curious what your shop qualifies for? Generate instant quotes with our automated loan pricer and get estimated rates, terms, and limits in seconds. If you like what you see, submit four months of bank statements and we can fund the same day or the next.
Factors to Consider When Choosing a Line of Credit for Your Auto Shop
What Are the Lender’s Requirements?
Before approving a commercial line of credit, a bank typically wants to see a high FICO score, a long time in business, collateral or a personal guarantee, and profits that hold steady year to year.
Auto shops, with their uneven months, rarely check every one of those boxes, and a shop with bad credit has even less of a chance. Overall, only about 13% of businesses that apply at banks are approved.
The bigger problem is timing. You usually don’t hear about a rejection until weeks after you applied, and by then you’ve lost that time and have to start over with another lender.
That’s why we advise reading each lender’s requirements first and applying where the requirements are realistic for your shop.
How Much Paperwork Does the Lender Require?
A lender’s advertised speed and its real speed are often two different things. Borrowers regularly tell us about lenders that promised funding in a day or two and still hadn’t paid out weeks later.
Rather than trusting a lender’s advertising, a more reliable test of how fast it will fund is how much paperwork it asks for, since every document has to be reviewed and underwritten before funds are released.
If a lender asks for mountains of documents, don’t expect fast funding.
Does the Lender Pressure You to Sign?
Watch how a lender behaves once it sends an offer. Low-quality lenders often set artificial deadlines, call or email repeatedly, or claim the rate won’t last, all to keep you from comparing offers.
A lender with competitive interest rates, on the other hand, has no reason to rush you into signing and will encourage you to compare its offer with others, so treat the amount of pressure as a rough measure of how competitive the price is.
Does the Lender Have Experience With Auto Shops?
Auto repair has its own cash-flow rhythm: shops buy parts before they bill for the repair and insurers pay collision work weeks after the car leaves the bay.
A lender unfamiliar with the trade may read those patterns as instability or weak margins and respond with a higher rate or a decline. Choose a lender that has funded shops like yours, because it will recognize them as normal.
10 Best Business Lines of Credit for Auto Shops
1. Redline Capital: Revenue-Based Lines of Credit for Auto Shops, Funded Same Day or the Next
We founded Redline Capital because we saw how hard it is for small and mid-sized businesses to qualify for bank financing. Banks are risk-averse lenders, so they set stringent requirements, ask for piles of documentation, and can take months to reach a decision.
Our goal is to make working capital quicker and easier to get. Auto repair shops are among the industries we work with, and some come to us after a bank has already said no.


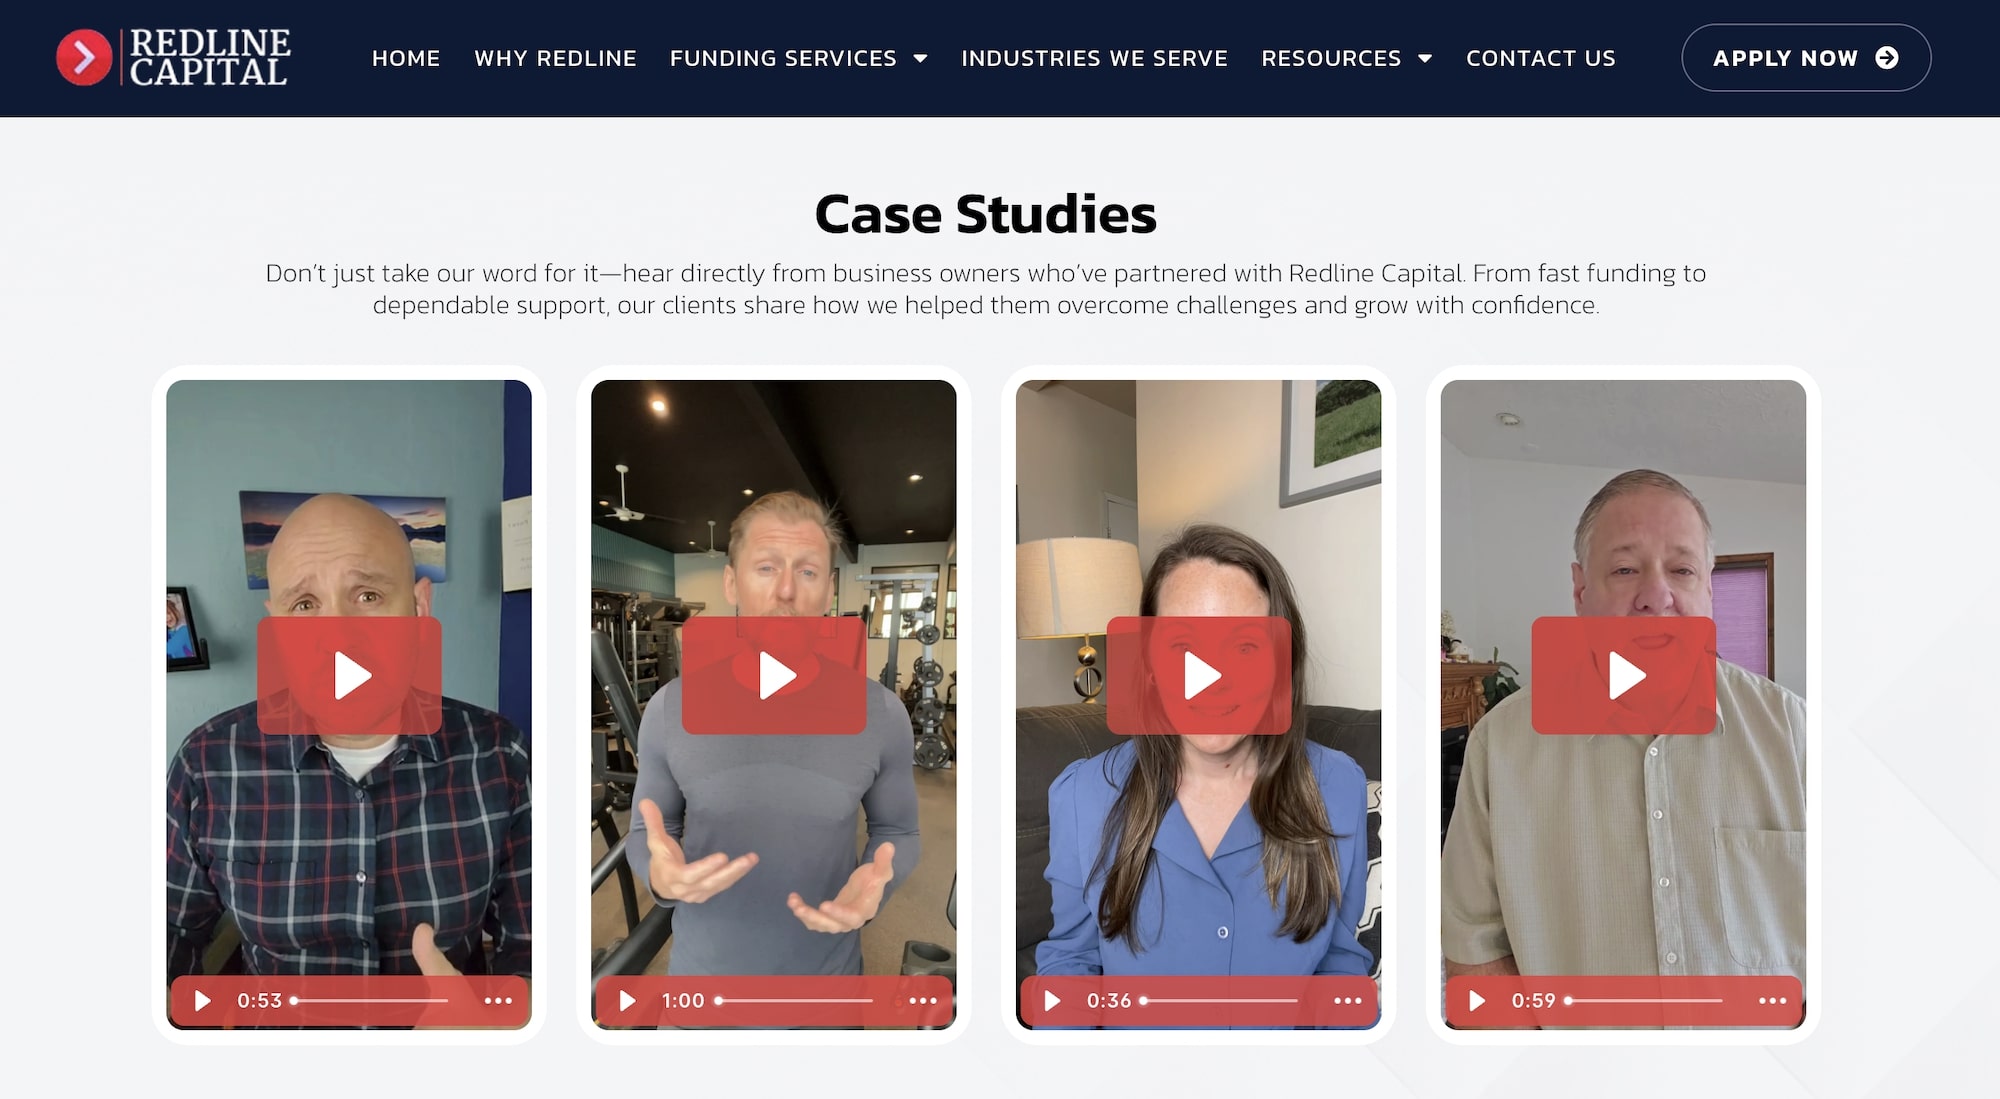
Check out our case studies page to hear what some of our borrowers have to say:
We Only Have Three Requirements, and We Approve Over 80% of Applicants
We built our requirements around the businesses that banks tend to turn away. Rather than reviewing your credit history and a full set of financials, we look at whether your shop brings in enough revenue and has been open long enough.
Here are our only three requirements:
- $30,000 or more in monthly revenue
- At least 12 months in business
- A U.S.-based business
You don’t need strong credit, a minimum profit margin, or collateral to qualify. We don’t set a minimum FICO score, so bad credit alone won’t keep a shop from qualifying, although a stronger business credit score can improve your rates.;
Because our requirements are so light, more than 80% of the businesses that apply with us are approved. If your shop doesn’t qualify for a line of credit, you may still qualify for other products, such as working capital loans, merchant cash advances, SBA loans, and equipment financing.
We offer both unsecured lines of credit, which need no collateral, and secured lines of credit, which can lower your rate.
We Only Need Four Months of Statements, and You Can Get Funded the Same Day or the Next
As noted above, the number of documents a lender requests tells you more about its speed than its marketing does.
We keep our list lean on purpose. To confirm that your shop brings in $30,000 or more a month, we ask for four months of bank statements and nothing else, so there are no tax returns, financial statements, business plans, or collateral papers to track down.
With so little to review, we can usually close a line of credit the day you apply or the day after.
We Help You Secure Lower Rates Than Other Lenders
Our offers don’t depend on pressure. You’re welcome to compare them with anyone else’s because we know that most borrowers end up coming back to us.
Part of the reason our borrowers get lower rates than they would from other lenders is the broker relationships we’ve built over the past decade. We’ve sent our lending partners (e.g., OnDeck, Rapid Finance, and Headway Capital) hundreds of millions in loan volume, which has brought them a steady stream of new borrowers.
Because of that volume, those lenders give our applicants lower interest rates and better repayment terms than a business applying directly generally would see, and we pass those terms along to you.
We Understand How Auto Shops Earn Money, So Normal Patterns Won’t Count Against You
Shops pay for parts and technician wages before the repair is billed and that creates large cash flow gaps.
We know these patterns well because we’ve worked with auto shops for several years. We don’t treat them as warning signs or penalize you for them, so it’s easier to get approved with us, and you’re more likely to secure a lower rate than you would from a lender with little auto shop experience.
Use Our Lines of Credit for Whatever Your Shop Needs
Our revolving lines of credit aren’t tied to a purpose, so your shop can spend them on anything it needs, such as:
- Parts inventory and supplies from your vendors
- Technician payroll and overtime
- Rent, utilities, insurance, and other operating expenses
- Diagnostic tools and equipment repairs
- Shop management software
- Advertising to bring in new customers
- Hiring and training technicians
- Covering cash flow gaps while waiting for insurance and fleet payments
For a major purchase such as a new lift, equipment financing is usually the better fit, and we can point you there.
Read more:How to Use a Business Line of Credit: Smart Uses & Mistakes
Get a Same-day Business Line of Credit at Competitive Rates with Redline Capital
If your shop brings in $30K a month and has been operating for at least 12 months, submit four months of bank statements and Redline Capital can help you secure a credit line at competitive terms.
2. Bluevine

Bluevine is an online lender that has delivered more than $16 billion in working capital to over 900,000 U.S. businesses, and it publishes a guide written for auto shops. Its line of credit goes up to $250,000, and a decision can come back in as little as five minutes.
Each draw has its own repayment terms, and Bluevine reports your repayment history to Experian, so on-time payments can help a shop build its business credit score. Bluevine says it charges no fees to open or maintain the line, and reviews report no prepayment penalties.
To qualify, Bluevine generally asks for a personal credit score of 625 or higher, at least 12 months in business, and $10,000 or more in monthly revenue. A single application also checks you for loan offers from its partner lenders.
Because draws are repaid over 6 to 12 months, each payment is larger than it would be on a longer schedule, and Bluevine requires a personal guarantee. The effective APR can also land well above the advertised rate once fees and payment frequency are counted.
3. Fundbox
Fundbox is a financial technology company that offers business lines of credit, alongside other financial products, with funding as soon as the next business day. The line goes up to $150,000, and each draw is repaid on a fixed weekly schedule, so it behaves less like a business credit card and more like a series of short installment loans.
To qualify, Fundbox generally asks for a FICO score of at least 600, three months in business, and $100,000 or more in annual revenue, although some sources list a lower revenue minimum. Those minimums are lighter than most banks’ requirements.
The weekly payments keep coming out through slow weeks, which can pinch a shop in a quiet month, and the effective APR on a draw commonly lands between 36% and 99% once fees are included. The $150,000 cap can also fall short for a shop making a large parts or equipment purchase.
4. OnDeck
OnDeck, an online lender that began funding small businesses in 2007, has delivered more than $15 billion to U.S. businesses. Its line of credit runs from $6,000 to $200,000 with no draw fees or maintenance fees, and repeat draws can arrive instantly through a debit card.
To qualify, a shop needs at least one year in business, a credit score of 625 or higher, and $100,000 in annual revenue.
The line has a 12-month repayment term, and OnDeck’s own disclosures show APRs well into the double digits, so compare the true cost before you accept. Because OnDeck lends directly, you also see only one lender’s view of your shop.
OnDeck is one of the lenders in Redline Capital’s network, so applying through us may get your shop a better rate than applying directly, because of the volume of business we’ve sent OnDeck over the years.
5. PNC Bank
Headquartered in Pittsburgh, PNC traces its history back to 1845 and now serves business customers across much of the country. Its small business lineup includes term loans, lines of credit, SBA loans, business real estate loans, and business vehicle loans, and its unsecured small business line of credit runs from $10,000 to $100,000.
Shops with assets to pledge can choose a secured line instead. That version is backed by business assets other than real estate, lets you make payments that cover only interest, and can double as overdraft protection on a PNC business checking account.
To qualify, PNC requires at least two years in business, and you’ll need a record of on-time payments going back at least five years. PNC also reviews your personal and business credit, your business financials, and your personal debt, and it looks for a profitable shop with stable or rising revenue and margins, plus a business credit history with no bankruptcies, tax liens, judgments, or lawsuits.
Those standards rule out newer shops and many owners with bad credit. A shop whose profits rise and fall with the seasons may also have trouble showing the steady margins PNC wants to see.
The costs and account rules add up as well. The unsecured line carries a $175 annual fee, and the secured line charges 0.25% of the committed credit limit each year, while every PNC line requires automatic payments from a PNC business checking account.
6. Rapid Finance

Based in Bethesda, Maryland, Rapid Finance has lent to U.S. businesses since 2005, and it sells term loans, SBA loans backed by the U.S. Small Business Administration, and merchant cash advances alongside its line of credit. The line goes up to about $250,000, and funding on most products takes anywhere from the same day to three business days.
For its line of credit, NerdWallet reports a minimum time in business of 24 months and $150,000 in annual revenue, along with automatic repayments from a business bank account. Some reviews list minimum credit scores as low as 550.
The two-year minimum rules out newer shops, and automatic repayments pull a set amount on a fixed schedule, which can strain cash flow in a slow month. Rapid Finance also uses a hard credit pull, so checking your options leaves a mark on your credit report.
Rapid Finance also works with Redline Capital as a lending partner, so applying through us may get your shop better pricing than applying directly, based on the volume of business we’ve sent them over the years.
7. American Express Business Line of Credit
American Express puts its business lines of credit, business credit cards, and checking accounts on one dashboard. The American Express Business Line of Credit goes up to $250,000, and each draw becomes its own installment loan repaid over 6, 12, 18, or 24 months.
Eligible applicants can get a decision within minutes when their business data and bank account can be verified automatically. To qualify, American Express asks for a FICO score of at least 660 and at least 12 months in business, and the required score can be higher depending on your credit history and your relationship with the company.
American Express publishes an auto repair business loans page, but it also states that not every industry is eligible for the line, so confirm that your shop qualifies before you apply.
That 660 floor is higher than the minimums at Fundbox, OnDeck, or Bluevine, and reviews note that American Express weighs credit history and business stability more than revenue, so a newer shop, or one with bad credit, may struggle even with steady sales.
8. Credibly
Credibly was founded in 2010 as RetailCapital and has offices in New York, Arizona, and Michigan, and it publishes a guide to business loans for auto repair shops. It also sells merchant cash advances and working capital loans, and its line of credit goes up to $600,000, comes as a secured or unsecured product, and can be repaid through weekly or monthly payments.
Approval is possible in as little as two hours. To qualify, Credibly generally asks for a credit score of at least 675 and $20,000 in monthly revenue, and it uses soft credit checks, so checking your options doesn’t affect your credit score.
That 675 minimum is higher than at most lenders in this comparison, so shops with fair credit may not qualify. Credibly also doesn’t finance startups, so a newer shop without an operating history may not qualify either.
9. Bank of America
Bank of America is one of the largest banks in the United States, and its Business Advantage unsecured credit line starts at $10,000 and renews annually, with a path up to $100,000. Shops that can’t qualify yet can start with a cash-secured credit line from $1,000, which is backed by a security deposit, and move up to the unsecured line later. For larger needs, the bank also makes SBA loans through its SBA Express program, which are backed by the U.S. Small Business Administration.
The unsecured line generally calls for two years in business, $100,000 in prior-year annual revenue, and personal credit above 700. The cash-secured line is easier to get, with six months in business and $50,000 in annualized revenue.
The two-year requirement and the 700 credit expectation rule out many newer shops and shops with bad credit. The cash-secured option also doesn’t add funding, because the deposit has to match the credit line.
10. Wells Fargo
Wells Fargo is one of the largest banks in the United States, and it offers a commercial line of credit in unsecured and secured versions. The unsecured BusinessLine goes up to $100,000 and suits day-to-day operating expenses, while the secured Prime Line of Credit extends to higher credit limits for established shops that can pledge collateral. The bank also sells term loans, SBA loans, and equipment financing.
BusinessLine eligibility starts at six months in business, and pricing is variable, running from the prime rate plus 1.75% to the prime rate plus 9.75% depending on your personal and business credit. Wells Fargo also requires a personal guarantee from any owner with a 25% or greater stake.
That rate range is wide, so a shop with thinner credit could land well above the low end. The line also carries an annual fee of $95 to $175 after the first year, and the paperwork list includes two to three years of tax returns and current financial statements.